Okay, so now that I’m a rich old retiree, instead of doling out a few bucks per month or per quarter from retirement savings to meet day-to-day living expenses, in 2014 I decided to draw down enough to cover the entire year’s living expenses, taxes, and insurance, dump it into checking, and hope it lasts 12 months.
Because a) I’m not very competent with math and b) I tend to overcomplicate things in my desperation not to make a mistake or overlook things, my budgeting spreadsheets have become hideously involved. “Tangled,” actually, is the word we might use. When I look back over them and try to remember why I made this or that decision, I can’t figure out what on earth I was thinking.
So, I decided to start all over.
Step 1 was to pose a series of questions designed to lay out the data needed to create a coherent, uncomplicated, nonstupid, and reasonably accurate budget. Videlicet:
1. What is the total amount that will become available from all sources (savings drawdown, Social Security, teaching) during 2014?
2. What are the routine monthly nondiscretionary costs?
3. What are the routine monthly discretionary costs?
4. How much was in the bank on January 1, 2014?
5. How much do the two spending categories really add up to by the month? (i.e., not how much do I think they add up to…)
6. How can I know how much is left at any given time?
7. Can I create a spreadsheet where I can just plug in monthly discretionary, nondiscretionary, and extraordinary totals (“extraordinary” = unexpected costs) and get a snapshot of where I stand at any given time?
8. How much, realistically, should it cost to live in 2014 (i.e., including extraordinary costs, taxes, and insurance)?
9. What is the difference between projected total 2014 funds available and the projected realistic 2014 cost of living?
Step 2: Fill in the answers:
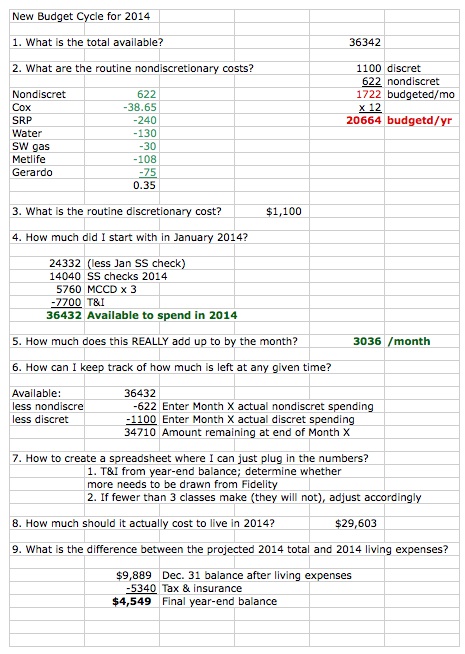 Step 3: Figure out a relatively simple way to keep track of expenditures so I’ll know whether a) this is right and b) I’m about to run into the red.
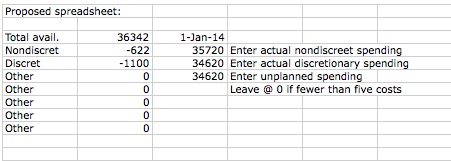 In this scheme, the first line of the spreadsheet shows the total amount I believe will come available over 2014. This includes 12 Social security checks and future teaching earnings for three sections. Because there’s a good chance I may teach four sections this year, the $36,342 shown on January may actually be conservative.
Now the idea here is to add up, once a month, all the nondiscretionary expenditures (utilities, long-term health care, yard dude) and enter that total each month; add up all the nondiscretionary costs (these would be the AMEX and Mastercard bills, since I charge almost all nondiscretionary expenses); enter (among “Other”) any extra incoming funds, such as the checks from Medicare and the Medigap insurer; and enter any extraordinary expenses, also among “Other.” Then keep a running balance in column 3.
Thus at the end of any given month, the balance should show how much money remains to cover 2014 living expenses.
The glasses, the ER visit, the eye specialist’s ministrations (much of which were disallowed by Medicare & Medigap), the contact lenses, a car repair bill, the landscape improvement needed to redirect rainwater away from the back patio and wall, extra pay for Gerardo to fix the landscapers’ screwups, a dental bill, and clothing to replace items that no longer fit after the 30-pound weight loss have already racked up a phenomenal amount of “extraordinary” bills — as much as I had planned on for the entire year. And they don’t include the $800 I’ll have to pay for the puppy a couple of weeks hence, plus the veterinarian’s puppy exam, plus the food and gear for the pup, plus the obedience training class, plus the remaining shots, plus the spay job. Pup may not need to be spayed until 2015. But she probably will come into heat by the end of this year. If so, she’ll have to be “fixed” forthwith.
All that nothwithstanding, though, when the January and February bills are plugged into the new spreadsheet, things look a great deal brighter than I expected:
 So the balance at the end of this month will be $31,164: more than the projected cost of living for all of 2014.
That’s not as cheering as it looks: to get the true picture, we have to subtract the cost of taxes, homeowner’s insurance, car insurance, Medigap insurance, and Part D insurance. That leaves us $25,824 to last from March 1 to December 31. That’s still slightly higher than the $20,664 budgeted for 2014 ordinary living costs.
Assuming unbudgeted “extraordinary” expenses will average out, over the year, to around $300 a month, the total cost of living should come to $23,664 in 2014. Even with taxes and insurance added, that will put me in the black this year. Anything left at the end of December will defray the amount of 2015’s saving’s drawdown. And every dollar that stays in savings now is a dollar that will help support me in my dotage.
That certainly is a huge improvement over the grim outlook I enjoyed in 2010, 2011, and 2012, when every goddamn month posed the question of how to make ends meet while living like an anchorite. In 2013, things were a little brighter — at least it didn’t look like my house was likely to be condemned for taxes. It may also just be that the convoluted system I’ve been using obscured the difference between the amount I would need this year and the amount I pulled out of savings. Either way, this year things look pretty good.
Probably it’s because the economy is better — investments have recovered so much that total savings are now almost back to where they were before the Crash of the Bush Economy, meaning that the overgenerous drawdown I seem to have made this year plus the amount that covers my share of the downtown house’s mortgage together do not exceed 4% of total savings. If I’m right that drawdowns can be much more conservative, it looks like things budgetary can continue as they are for the foreseeable future.
Bueno!


