Coffee heat rising

This, That, and the Other

Gotta hurry! Today I have to write chapter 2 of a client’s book, his check finally having arrived on the scene.

Up early and off to walk the dog by 5:30. Breakfast on the back porch, interrupted (as usual) by the roar of a flicking helicopter. This time it didn’t go away or hover over the war zone at 19th and Dunlap or park over the neighbor’s house, but kept buzzing back and forth, low to the ground. MedicEvac??? Get up to check.

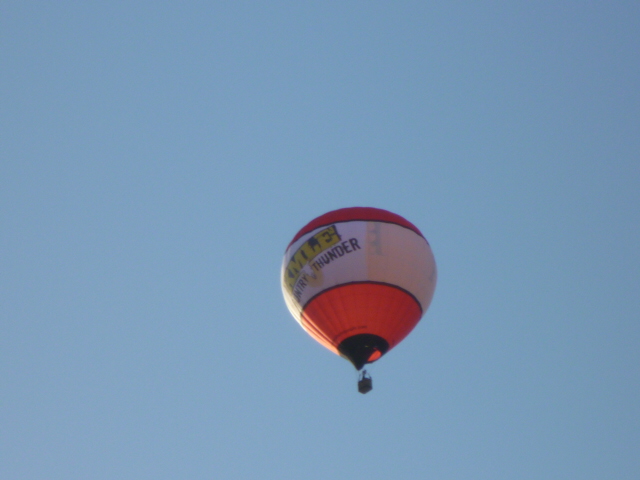
It’s this splendid balloon floating past, accompanied by a copter buzzing like a turbocharged mosquito around it! What a hoot, eh?

Once I bought my ex- a balloon ride for his birthday. They invited me to climb into the basket, too. It was great fun. I think these things are the most hilarious and wonderful form of travel invented since the bay mare.

Tried to snap a photo of the balloon and the copter in formation, but by the time I got to the office, grabbed the camera, and ran back outside, they were too far away to get a really good shot. This was about the best I could do:

(Click on the images for larger, sharper versions.)

Working out of one’s home has a distinct disadvantage: when you’re in an office, you attend to office business all day. When you’re at home, you’re distracted by all the chores that need to be done. Sometimes I feel like I’ve been laboring like an animal and then at the end of the day feel like I’ve accomplished essentially nothing. Certainly nothing payable. Yesterday I decided to keep track of what the heck I do that kills so much of my time. And…no, it’s not like I’m doing nothing:

• Walked dog
•
Fed dog
•
Fed me
•
Read New York Times
•
Watered roses
•
Set soaker hose
•
Watered a little on west side
•
Read Eng 235 paper
•
Updated Quickbooks (after a month-long lapse…)d
•
Transferred funds from PayPal to CED checking
•
Updated records on investments
•
Filed a mountain of paperwork
•
Hassled with AMEX over an incorrect debit
•
Bathed, washed & dried hair, painted face
•
Raced to campus
•
Wrestled with Registrar over incorrect withdrawal of 235 student
•
Hauled student’s paperwork all over campus
•
Met two classes
•
Updated students’ grades; reported to graders on student progress
•
Drove to credit union, deposited money
•
Stopped by Fry’s Electronics on way home; bought printer cartridge, notecards
•
Bolted down microwaved dinner
•
Checked e-mail; skimmed Google News
•
Cruised Zillow
•
Raced to campus, just made it to real estate class on time
•
Sat through class
•
Drove home
•
Consumed two Camparis on the rocks while watching old episodes of My Name Is Earl
•
Dropped into the sack around 11 p.m.
•
Attempted to read detective novel; fell asleep after about 15 words

So…today, damn it, I’ve GOT to get some work done!!!

And it must be admitted that work is the last  thing I want to do. The day is just gorgeous. It beckons: Come to me, come to meeeee….

Water bill is high, it develops, because the last big power outage somehow reset the watering system to come on every day instead of every other day. That plus the fact that I’ve decided to actually water the plants has revived the landscaping. Quite a few moribund plants have come back to life. I’d about given up this rose for dead, for example:

Those blossoms are more fuschia-colored than orange: early-morning light through mare’s tails. And here’s a little beauty from another rose that really suffered last summer. In January, I decided not to prune this bush because it was so exhausted—better, I figured, to just leave it alone for a year. What it needed was not pruning but water:

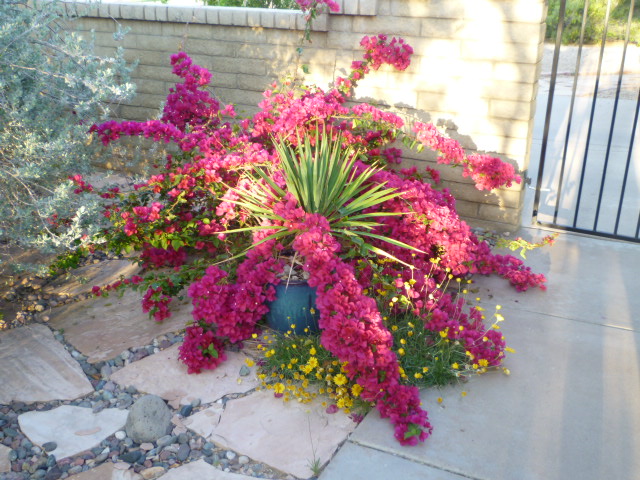
The bougainvillea’s gone insane this spring:

Isn’t this cute? It’s growing on a weed-like thing that sprouted from the shade-loving seeds I sowed in the backyard flowerbed last fall, none of which germinated until the days started to get longer few weeks ago.

No clue what the thing is. Then we have this…

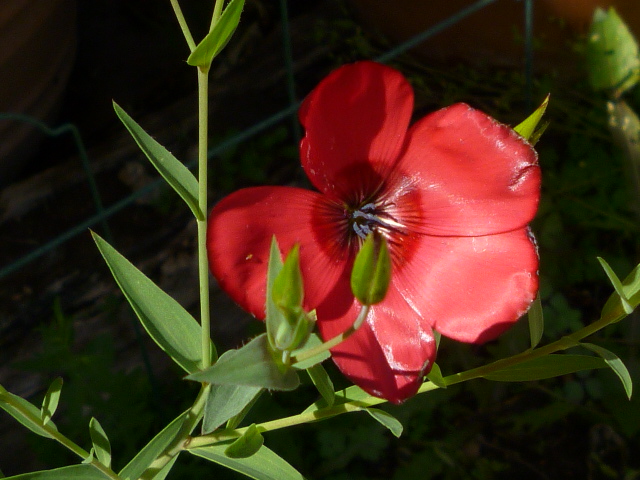
…and this…

And these…

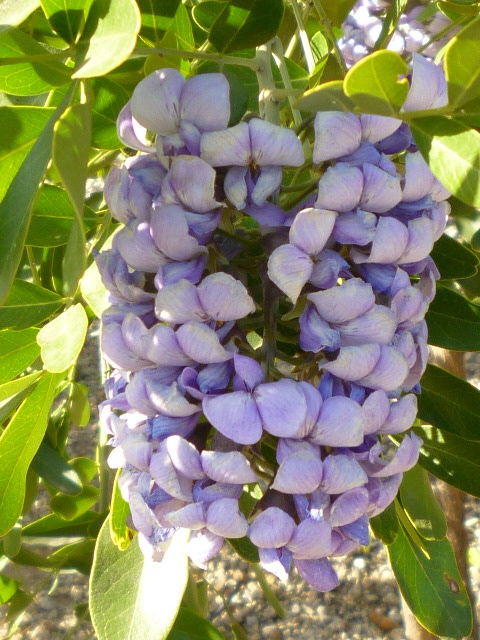
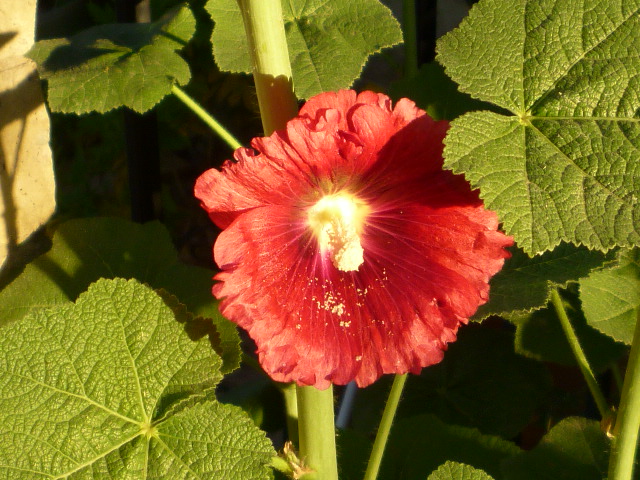
And this…

And these…

And Charlie contemplating the next spot to dig a nice hole…

Speaking of Charlie, he’ll be here soon. MUST get some work done before my son shows up with that dog!!!

A$k Lady Karma, and ye shall re¢eive

For hevvinsake! You’ll recall how I was whining about my penurious income, part of which is a piddling $1,080 Social Security benefit? Well, Lady Karma must have read that blog post.

In this afternoon’s mail, along comes a missal from the Social Security Administration. I cringe when I see yet another summons from the Feds: it usually means another frustrating ride on the bureaucratic merry-go-round. But not always…

Periodically we reexamine our records to see if there are any additional benefits due. As a result of this examination, your monthly benefit amount has been increased to give credit for months of entitlement before you reached full retirement age, 66, for which monthly benefits were not payable. You also have been given credit for additional earnings which were not included in your previous computation.

To coin a term, huh??

You will receive a payment on or about May 9, 2012 for $1317.50. This payment includes both your new regular monthly benefit and benefits due from May 2011, the date of the earliest increase described above, through April 2012.

Seriously? You mean I could buy a pair of shoes? Dang!

After that, you will receive your monthly payment of $1,115.20.

Hot damn! They’re giving me a $35/month raise!

Hey. Every little bit counts. It’s better than a $35 cut. Thirty-five bucks will buy a meal out. It will pay the increase in the Cox bill for about a year. It will cover the increase in the amount I’ll have to self-escrow to cover the newly bloated homeowner’s insurance premium. Too, too excellent.

Money Worries: I’ve gotta stay away from the computer

Probably I’m better off if I don’t know. Sitting in front of the computer mulling over the money worries is not helping my mental health.

Any way you look at it, there’s no way my savings will support me for the rest of my life, unless I die tomorrow. Nor is there any way my lifestyle is going to get any better. I am so damn sick of pinching pennies…my whole life has become pinched. And especially I’m sick of working like an animal for sub-minimum wages. Our current client hasn’t paid us; I sent him a bill payable net ten days and haven’t heard a word. Ten days, however, won’t be over until next Friday. Meanwhile I didn’t finish the work I was supposed to have done for him because the perfectly excruciating piece of ersatz lit-crit I was editing expanded to fill all space—I’ll make a grandiose $360 for 30 hours of work on that thing, and the real truth is, it  probably took more than 30 hours to drag through. Between that, the nonpaying client’s work, and the Holy Week frenzy of singing, I haven’t been able to break loose enough time to work on the real estate course.

I feel pretty discouraged about the real estate scheme, because I kinda doubt that I’ll make any more at that than I do at my various other schemes, largely because I’m not much of a people person.

Consequently, a view of my financial future goes beyond “pretty” discouraging to “radically discouraging.”

Yesterday I asked myself if I might take a small drawdown from savings to give myself enough extra money that I could pay the bills and have just a little bit extra to spend on things like clothing, shoes, an occasional concert or visit to a museum, or maybe just not having to feel strapped after the car has to be fixed. Math not being a stronger point with me than people skills are, I had to think this through each step of the way.

First, Social Security covers less than half my expenses, which include a $734 payment toward the downtown albatross house. Teaching income is peanuts, and because it’s extremely irregular (I’m actually paid only 8 months out of 12, and for long stretches no two checks are the same), I put that into a money market account and then transfer a set amount to my checking account to cover expenses. Right now, the amount is $2,050 a month. It just covers expenses; in the summer, now that utility bills have gone up, it actually does not cover expenses (my winter bills are now almost as high as summer’s sky-high bills were two years ago). Nor does it cover expenses in a month like this one, when I get hit with a $450+ car repair bill. One out-of-routine expense will put me in the red, and “routine” does not include a meal in a restaurant, a hair styling, a trip to the botanical garden or a museum, a concert that I have to pay for, a day trip to a tourist attraction.

So the first question is, while I’m teaching seven sections a year, how much beyond teaching income do I need to pay my bills? Right now I’m pulling $930 a month from a long-term emergency savings fund (every month is an emergency when you’re permanently unemployed), which resides in the credit union making zip. Sooner or later, I’m going to be forced to buy a new car, at which point I will need that money to pay for it—seeing it drop by almost a thousand bucks a month makes me cringe.

Another way to look at this: presently I’m running in the red.

Retirement savings average about an 8 percent return, so a modest drawdown (up to about 4%) should not reduce principal over the long term. Can I draw down from retirement savings without having to eat into principal?

Another $500 a month would cover the rising bills (my homeowner’s just went up another $55) and give me enough extra to enjoy life in a modest way. It wouldn’t cover expenses during the summer or during the month-long winter break, when I have no income other than Social Security, but it would be better than nothing. What percent of my savings would I have to draw down to engineer a net $500/month increase?

Okayyyy…. Let’s think about that.

A gross drawdown of $20,592 a year is 3.69% of savings. That’s almost four percent (the amount money advisers suggest to make savings last for most of your remaining years—and based on family lifespans, I expect to live into my mid-90s). Almost four percent while I’m teaching the maximum allowable number of classes!

Holy God! Does that or does that not mean I will end up in freaking poverty when I can no longer dodder into a classroom? Speak to me, ô Oracle of Excel!

Right now I need $3,040 a month to cover everything (that amount can only go up, but let’s avert our eyes from that inconvenient truth).

Got that? A near-four percent drawdown will not allow me to cover my bills if I’m not teaching! That $530 shortfall x 12 months comes to $6,360 a year, the equivalent of 2.65 sections of freshman comp. What it means is that I will always be short of what I need to live on unless I teach forever, until I die.

Uh huh. Can you imagine a 95-year-old Ph.D. in English getting hired to teach roomsful of fractious 19-year-olds?

How much will I need to cover my bills if and when I can’t teach anymore?

Lovely. I will need over 5% of savings to live like an ascetic. And I hate living like this.

Having seen what happened to an acquaintance when she ran out of money at the end of her lifetime, however, I can assure you that I do not want to draw down more than 4% of retirement savings! Better you should shoot yourself than go through what that woman did—and she had friends running interference with the horror show for her. If you were all alone, like, say, me…you truly would be better off dead than old.

Most Americans would be better off dead than old, IMHO. That’s the nature of our society.

Oh well. Moving on.

So, suppose I cut the proposed pay increase from $500 a month to $250 a month? Then how much would I have to draw down?

Okay. I could increase the monthly budget by about $250 if I continue to teach 3 +3 +1 and draw a little over 3% from savings. That’s more reasonable. But…what happens when I can’t teach anymore????

Wow! To get by with just $250 added to my present “income” from savings after I can no longer teach, I will have to draw down almost 6 percent from my savings.

That’s assuming a 20% tax rate, which is about what I’m paying right now. I ran the figures at 15%; that made almost no difference in the amount I would have to draw down to survive. It’s sure unlikely taxes will ever go down. And you can be sure expenses will never go down. Matter of fact, that 6 percent drawdown does not account for inflation.

We’ve seen the vagaries of the economy: what goes up must come down. I lost $200,000 in the crash of the Bush economy. It’s pretty well come back over the past four years—only because ever since I was laid off I’ve struggled to avoid drawing  money from investments. But all it will take is one more (inevitable) market drop, and the amount I’ll need to take out of savings will be one hell of a lot more than 5.7 percent.

I’m screwed. Unless I die soon, screwed.

Of Music, Puppies, Popcorn, and Whiskey

The All Saints Choir, under the direction of the truly astonishing Scott Youngs, performed a spectacular concert today, alternating between us (choir) and several really lovely soloists and accompanied by a string ensemble. It was an exciting and wondrous experience, one of those moments that makes one feel privileged to be alive. We got to sing d’Astorga’s Stabat Mater, Victoria’s Lamentations, and Hasse’s Miserere Mei. If you live in the Phoenix area, even if you’re not religious (which I’m not, especially) you should keep an eye on this church’s music program, which includes professional singers and extracts professional-quality sound out of the mostly amateur music-lovers in its choirs. In particular watch for special performances around Easter and Christmas. I started attending All Saints after I wandered in one Sunday and realized you get a high-quality chamber music performance at nearly every service—and that’s not an exaggeration. If you love music, this is a place to be.

So I was looking forward to coming home, climbing into a pair of cutoffs, pouring a glass of wine, and spending the afternoon reading about real estate transactions. Or maybe reading inchoate magazine articles from my budding journalists. Or maybe ghostwriting another chapter of our amazing new client’s memoir.

No such luck.

There’s a reason M’hijito has taken to dubbing Charley the Golden Retriever with the “bad dog” title, Charley Manson. When I opened the kitchen door from the garage, a fine gut-wrenching stench greeted me. Charley had left a deposit the size of a loaf of WonderBread in the middle of the kitchen floor!

Miserere indeed! Naturally, he had to polish it off with a little diarrhea. Lovely. As we scribble, the whole house reeks of its stomach-tossing perfume.

Mercifully, he’s no longer having to stay in his crate, so the mess was confined to one pile and not smeared, as it was the last time, all over him, his (now former) bed, his crate, the floor, and the adjacent wall. And thank goodness the weather is nice: every door and window is open, and every fan in the house is going full-blast.

It’s not his fault: expecting to be gone about two hours, I fed him shortly before leaving. Bad move. We actually convened for three hours, and that was just longer than even an almost grown pup can be asked to maintain his doggy integrity.

{sigh}

This calls for something stronger than old-vine Zinfandel.

As soon as I can bring myself to re-enter the kitchen, I’m gonna pop a pan of corn, pour a bourbon and water, and…yes, real estate. I believe real estate will be this afternoon’s reading matter of choice. It has a positive ring about it: there’s a distant possibility that maybe, just maybe, this could be an avenue that would allow me to earn enough to make ends meet.

Maybe.

Entrepreneurs: Crystal Stemberger’s Blogging Empire

Need a role model? Here’s one for you: a live wire who’s  earning 15 to 20 grand a month in the blogging biz. No, that’s  not a typo: in February she netted $15,600.72; in January, $17,979.04; in December (“best month ever in my 29 years on earth!”), $22,284.31. Of course, we’re speaking of Crystal Stemberger, proprietor of Budgeting in the Fun Stuff. She established BFS a scant two years ago and quickly turned it into one of the top personal finance sites in the blogosphere. Meanwhile, she was building a blogging empire that included an agency that brings together advertisers with bloggers whose sites fit their products. By July of 2011, she found herself in a position to quit her day job, and seven months later, in February of this year, her husband Len joined her full-time in running the business.

Let’s hear what she has to say for herself…

FaM: You started Budgeting in the Fun Stuff with the express goal of finding a way to get off the treadmill. Had you thought of the ad agency idea at that time, or did you conceive of monetizing your online enterprises in different ways?

Crystal: Well, the real reason I started Budgeting in the Fun Stuff was because of a post at Get Rich Slowly about a lady who made $1 million off a business and then hired a housekeeper and a lawn service. She got jumped by the readers, who were all over her saying she shouldn’t be hiring domestic help, that it wasn’t frugal, and she had no business spending her money that way. I thought, “It’s her money, and she can use it as she wants!” It really made me mad that people would presume to pass judgement on her choice to use the income she had earned. So, I started Budgeting in the Fun Stuff to show you can and should do what you want with your money, as long as you manage it responsibly.

FaM: It certainly has come a long way from that beginning. Did you have any idea that you could build such a successful business from blogging?

Crystal: When I started, I didn’t have a goal in mind. I didn’t know how much you could make with a blog. But then I started getting offers from advertisers, and I discovered that I really like negotiating. Pretty soon Budgeting in the Fun Stuff was making good money.

FaM: You started Crystal for Hire in April 2011.

Crystal: Yes. That April Bucksome Boomer asked me to manage the advertising on her site. She said she dislikes negotiating and asked if I would do it for her. I said yes, and now Mr. BFS and I have have 325 client sites!

FaM: I’m with her—I hate arguing over fees. Bet that’s true of a lot of writers and bloggers: if we were good at marketing, we wouldn’t be sitting in our garrets trying to make a living with our keyboards.

Crystal: I had no idea how many bloggers are introverts. But when you think about it, it’s so obvious that it’s a big duhh! I was the other way around. I talked all the time; that was one reason why I started Budgeting in the Fun Stuff. My friends and family sort of wanted me to shut up about money.

FaM: It seems like a natural, then, as a business.

Crystal: There are other ad agencies for bloggers. I didn’t know until I started doing this. But they don’t do what we do. Instead of providing just an ad person, we work for both sides: we make it easier for the clients because they don’t have to do anything, since we answer all of the e-mails, and at the same time we simplify things for the advertiser. Advertisers’ representatives don’t want to tell you much when you’re the person running the blog. But when they go through us, they’ll negotiate based on the advertiser’s budget. I like the ones who will tell us what their budgets are.

And since I make more if the client makes more, even though we appear to be working both sides of the aisle, I don’t think it’s a conflict.

Sometimes I know when an ad rep is lying. My favorite is when they forget they’ve been working with Mr. BFS or me and will try to work with me for another site and they’ll lie about, say, what their client will pay. As far as I’m concerned, all my bloggers have Stemberger as a last name, and every one of them is a member of my family. You don’t cheat my family members.

FaM: So what does a typical workday at BFS look like?

Crystal: I usually work from 8:00  or 9:00 to 4:00 or 5:00; then it’s back to work from about 9:00 p.m. to 1:00 a.m. On average I put in 12 to 15 hours a day Monday through Thursday.  Then on Fridays it’s only 6 to 8 hours, and on weekends, another 6 to 8 hours if I can drag myself away. I never stop working. Even  seeing things at the movie reminds me of what to do back here. It’s like having a quiet a baby…can’t imagine having kids…having my mind taken over by something else like this would kill me.

FaM: What were you doing before you made your escape?

Crystal: I was a custom forms programmer at a car dealership software company; I was the one who told who told the computer where to put your name address & all that stuff on the forms that you have printed up during a car deal. Half of it was customer service, and  half of it was advanced data entry, and it paid about $35,000 a year.

FaM: When did you realize Mr. BFS could join you in the business? And what was he doing before?

Crystal: We only had that idea about the end of November.

I was getting overwhelmed with 130 or 140 clients. Because I was working 100 hrs a week, I started talking about hiring someone. One day he woke up and said “Could you hire me”? He was a school librarian, so he had the record-keeping experience. He took over the record-keeping and that relieved me of two hours a day, right off the bat. He was doing that after work. When we realized I made $15,000 a month over the previous quarter, we decided it would be worth having him work full-time on the business. Before it took off, we’d only been making $5,000 a month combined from our day jobs.

Now we’re partners. He does the record-keeping and answers clients’ ad e-mails; I do the group ad campaigns and hand-holding. The two aspects of the business reinforce each other. It’s been amazing; it worked much better than I ever imagined. We separated our tasks so we wouldn’t be stepping on each others’ toes—we really don’t even have to talk to each other if we don’t want to.

FaM: How are you planning to deal with Google’s embargo of sites that publish paid links? I understand you recently ran into a rough spot over that.

Crystal: At least 20 of my bigger clients were hit; suddenly their Page Ranks dropped from 4 to 0 or from 3 to 2. It was a difficult time, because it coincided with my grandmother’s passing. This is the first week where things were going along normally. Then our new dog went nuts, but that’s another story.

I think people are overreacting. Not that many advertisers are changing their ways. Because of all the panic and because people tend to succumb to groupthink, I won’t know the consequences of this until the end of April. That will tell us if we hit the $10,000 level. We have to hit $10,000 a month to cover taxes ($3,500), basic savings ($3,000), and our normal expenses ($3,500); we target $15,000 to pay down the mortgage even faster and start saving for a new home.

FaM: Do you think this policy can be challenged effectively? It seems like constraint of commerce…possibly bloggers will get together for a class-action suit someday?

Crystal: No, I don’t think it can be challenged well because it only affects Google Page Rank.

My way of challenging it is to say screw Page Rank; let’s look at other ways to assess sites. I’m pushing MozRank and domain authority, other good metrics. I’ve sold ads on just domain authority alone. You and I have huge domain authority, for example; that can’t be taken away by Google. I want to give Google less credit. Clients with big PageRanks, 3 or 4, will still get the majority of ads, but others will do OK, too. Things will balance out.

FaM: What do you see for the future?

Crystal: I’m going to focus on quality clients. My goal now is not to expand, but to find our core group and stick with that. I started it as a one-on-one thing; I like my customer service and my business model. I think further expansion would take away from that.

Group campaigns are about 10 to 50 people, and I only do a few of those a month. One goal is to teach clients that they must forward the e-mails and letters from advertisers to us. The big money is to be made when people contact you and then we negotiate the best terms. Group deals are just icing.

In our personal lives, we’re already looking at a new house, since prices are so low right now. We can get a 3,500-square-foot house for $180,000! We’re looking for four bedrooms and a big gaming room. Sadly we do not have basements in Houston. Recently we learned that mortgagers don’t want to lend to business entrepreneurs—the “self-employed”—until they can see two entire years of steady income. So if we’re to buy a house before then, we’ll have to pay in cash.

Overall, we’re keeping cash on hand; we could live off our savings for six to nine months. We have $20,000 saved for hard times and $30,000 for the house payoff or for the down payment so far on the new house.

It was time for Crystal to get back to work, so I offered my thanks and let her off the phone.

One thing that our conversation makes clear: quitting the day job is not necessarily a way to work fewer hours. When you’re your own boss, you have the toughest boss in the world. But if you can work smart and you’re willing to work hard, you can make a living in the blogosphere—and then some.

Disclaimer: Crystal serves as Funny about Money’s ad agent.


Pasta-free Eggplant Lasagne

My friend La Bethulia dropped by the other day and left me with two lovely fresh eggplants. Wanted to cook them up and freeze them, but since I have more than enough ratatouille in the freezer, wasn’t sure what to do with them. At last weekend’s Farmer’s Market, though, I came across a guy who was selling what he called “eggplant lasagne.” Could I make that?

Quite a few recipes for concoctions by that name inhabit the Internet. I downloaded one from Epicurious, because I had most of the ingredients on hand. The only thing it called for that I didn’t have was ricotta…but I figured a workaround. It turned out really well. Here’s how it came down:

You need:

Two eggplants, sliced lengthwise into quarter-inch-thick slices
Salt
Thyme
Marjoram, oregano, or mixed herbs (I used herbes de Provence)
half an onion, chopped
a couple of garlic cloves, minced
1 egg
1 cup Greek-style yogurt
a roll of mozarella cheese, sliced up
2 16-ounce cans diced (or other) tomatoes
1 small can tomato paste
splash of red wine
olive oil
1/4 cup grated Parmesan cheese plus more as topping
canned or bottled roasted peppers

Preheat the oven to 450 degrees.

Salt the eggplant slices generously. Skim the bottom of a large rimmed baking pan or two smaller pans with olive oil. Place the eggplant slices in a single layer in the pan; rub the top sides lightly with more olive oil, and sprinkle with thyme. Bake the eggplant in the hot oven until browned and pliable.

Meanwhile, sautée the chopped onion in some more olive oil. As the onion begins to brown, add the garlic, stir a bit, and then stir in the canned tomatoes, the tomato paste, and (if desired) a slosh of red wine. Allow to simmer for a few minutes, until you’re ready to assemble the casserole.

In a small bowl, mix the egg, 1/4 cup Parmesan, and the yogurt together well. Add about a tablespoon of herbes de Provence and mix this in, too.

When the eggplant slices are done, remove them from the oven and turn the heat down to 375 degrees.

Use more olive oil to grease an oblong baking dish. Layer enough eggplant to cover the bottom of the dish. Spread about half the yogurt  mixture over the top of this layer. Spread about half the tomato mixture over this. Spread sliced mozzarella over the tomato mixture. Lay several canned peppers atop the cheese layer (slice them so they’ll lay flat).

Add another layer of eggplant, followed by the remaining yogurt mixture, then a layer of mozzarella (if you still have any), and the remaining tomato sauce. Sprinkle grated Parmesan cheese generously over the top.

Cover the pan with aluminum foil and bake at 375 degrees for about 15 or 20 minutes. Then remove the foil and bake another 15 minutes, until bubbly and hot all the way through.

This turned out to be amazingly delicious. Served with a green salad, it made enough to feed a guest for lunch and still have plenty to freeze in six or eight individual  portions.

You could add any number of other goodies to it: mushrooms, Italian sausage, a layer of spinach, a sprinkling of broccoli. And it’s gluten free. Try it out!