It’s 10:00 p.m. and I just finished the last revamped syllabus for the summer courses, which begin to incorporate my various schemes to make life terrifying interesting for my students. Been a bit silent on the blog because of the workload and the various adventures.
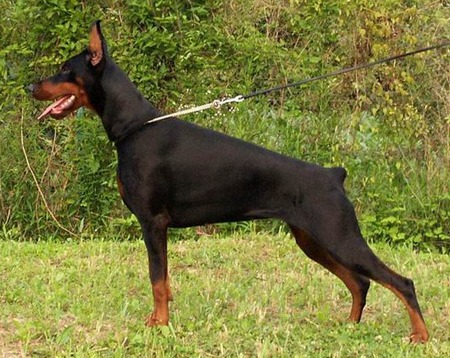
This morning my friend KJG came into town to socialize. She lives on the far side of the galaxy, halfway to San Diego, and so getting together can be a project. She brought her doberman pinscher along to schmooze with Cassie the Corgi. That was entertaining.
KJG’s dobe was a rescue dog that came to K and her husband with some serious behavioral problems. Today, though, the dog is impeccably well mannered. She’s mellow, quiet, and amazingly intelligent. Amazingly alert, too: very little gets past this animal.
Contemplating that very beautiful beast, it crossed my mind to wish I could still handle a big dog. As much as a large, powerful animal can be a challenge, it’s also reassuring to have something that will take out an intruder or die trying. Cassie slept through the guy trying to get in the side door a while back and remained silent while the alarm was squealing. KJG’s dog would have shot out of the bedroom and down the hall before I could’ve regained consciousness from the deep sleep that the door alarm interrupted.
A week or ten days ago, a couple of guys practicing the same MO—quietly breaking in at four in the morning—tied up an elderly couple and beat the bejayzus out of them. Imagine beating up a pair of 80-year-olds!
Nothing like a little meth to cut the boredom factor.
Speaking of the which, yesterday along about 2:30, after I’d come home from eight hours of driving around the city, I picked up the phone to chat with La Maya. Carrying it around the property, I walked into the garage for something and remarked that Phew! It smelled like something had died out there!
La Maya said she’d smelled a bad odor when she got home, too: when she walked from the garage through the courtyard into her house, she thought she smelled gas.
I said it didn’t smell like gas; it smelled like sulfur. And yes, it was indeed outdoors…I could smell it in the side yard and in the sheltered back patio.
But by the time I got inside, the stench had wafted into the house so that the family room and dining room stank to high heaven! Dayum!
La Maya also could smell it at her house. We debated whether we should report this, and if so, to whom. Ultimately we decided she would call Southwest Gas and I would call the City.
The City sent an engine full of firemen, who did nothing.
Southwest Gas sent a guy who inspected both houses and the gas lines in the alleys. He couldn’t find a gas leak. He agreed that he didn’t think it smelled like natural gas and speculated that it could be sewer gas released by some of the construction in the area.
I said I used to live near 15th Avenue and Osborn, where, because an excess of high-density housing has overwhelmed the sewer system, the air stinks of sewer gas most of the time. So I know what sewer gas smells like, and that ain’t it.
He allowed as to how it didn’t smell exactly like sewer gas to him, either. Whatever, he opined that it was not flammable and that it was outdoors, and so he went on his way.
A fair breeze was blowing in from the southwest, meaning we were upwind from the nearest construction, about a mile away. And also meaning it was blowing in from the gang-infested slums that have risen from the blight between us and the freeway. I suspect we were smelling meth in the cooking process.
It’s not the first time a whiff of it has perfumed the family room, either. I’ve smelled it several times over the past few weeks. Figured it was eau de doggo, since I haven’t committed an excess of cleaning while I’ve been working myself stupid lately. But Cassie is not a smelly dog at all. If she smelled like that, I’d have noticed the odor on her, not in the air.
gaaaahhhhh! I need to move away from here! Sure would be nice if I could afford a comparable house in a safer part of town. Or a safer part of the world.
But I can’t.
Makes a large dog with sturdy fangs and hair-trigger nerves look like a charming pet.
This is another guest post by a delightful graduate of my magazine writing course, Anita Martinez. It’s not easy to write humor. Let’s hope she keeps writing! 😀
We were a young couple at the time, having our first home built. This was an exciting event in our lives, interlaced with stress, especially when we had to stay at my in-laws’ home during the process.
For the most part, I got along fine with my in-laws, so it wasn’t too bad at first, in spite of the cramped quarters. I soon found out, however, that hot water for dishes, bathing and showering was a commodity my mother-in-law guarded ferociously. So I figured out a strategy.
Early dawn found me awakening before the rest of the snoozing household, armed with a towel and shampoo. I was thankful my father-in-law’s loud snoring muffled my stealthy entrance to the bathroom and shower.
A dry, cracked bar of Ivory soap lay in the soap dish, waiting to be frothed. I turned the squeaky shower faucets, and a dribble of lukewarm water greeted me.
As I basked in the showerhead’s trickle, my eyes wandered to an object upon the window ledge, directly above me: a smiling ceramic monk, complete with dangling rosary and cross. He had a hard-to-reach opening on top of his belly. I tip-toed and struggled to place my fingertips inside it. He was filled with water. Oh, holy water, was my thought. I must bless myself with it every morning and toss up a prayer that all goes smoothly with the house construction.
I followed this new-born tradition every morning: sneak into shower, plunge fingers in the happy monk’s sacred vessel, cross myself fervently, and pray.
One morning, as our extended stay neared its end, I must have been more alert than usual. As I showered, I noticed the ceramic monk facing me, bearing his happy Bob’s Big Boy grin. His protruding belly displayed printing I hadn’t seen before. In large, uppercase letters, were the words CHOPPER HOPPER. My brow furrowed as I pondered: CHOPPER HOPPER? What could that mean?
With a growing sense of dread, I outstretched my hands, groping and grabbing the grinning monk, whose cold water sloshed upon me. I peered down at the contents of his belly: my father-in-law’s dentures. I had been blessing myself with Efferdent and remnants of beef stew.
O…M…G…. I can not believe I worked on course prep until midnight, bolted down a few bites of nondinner, fed the dog, wrung the dog out, and then read copy until 1-flicking-30 in the morning. Back at it by 5:30 ayem.
Just finished plowing through the paid detective novel, absorbed a Guinness with some cheddar, a handful of baby romaine, and a pile of olives niçoises, and now am about to go to bed. How many hours of the past 24 have I been working? It’s 2:19…hmmm… about 20.
While driving around this morning, I happened to hear an NPR report on The Burning House, a site whose proprietor poses the seemingly simple question, “If the house were burning down and you had to get out right now, what would you take with you?” Good question: if you have to grab and run, what do you grab?
Turns out that’s not such a simple question, as Here and Now’s Robin Young learned when she interviewed proprietor Foster Huntington. The answer to “what would you take” is surprisingly personal, and it reflects a lot about an individual’s character, priorities, and social circumstances.
Various PF bloggers have held forth on the idea that you should have a box of key documents and cards ready to grab in an emergency—sorry, friends, but I can only recall having read those posts and don’t remember where they surfaced. I imagine some of my faves have written about these issues: J.D. Roth and the Ineffable Evan, both men of an eminently practical turn of mind, and possibly Frugal Scholar, who has lived through a major natural catastrophe and whose daughter was in Tuscaloosa during the recent terrifying storm.
What jumped to my mind the instant Robin Young asked “what would you take with you” was the dog. That’s all: the dog. The prospect of rummaging in the office closet for the box of treasures as the draperies are catching flame…not good. Snabbing the laptop or disconnecting the desktop and hauling one or both out the window (along with me and the dog): amazingly bad idea. Grab the dog and run!
Here’s what I think about this business of rescuing crucial documents: Carbonite. Carbonite and a scanner.
Get yourself a subscription to Carbonite’s lowest-end data backup software (amazingly cheap) and a decent scanner, which you probably already have on your printer. Tattoo the Carbonite password on the bottom on the bottom of your foot, so as never to lose or forget it.
Scan every important document to disk: family members’ birth certificates, parents’ death certificates, Social Security card, current credit cards (front and back), receipts for the wife’s diamond engagement ring, whatever. Scan every other important receipt, tax return, and crucial financial document. While you’re at it, scan your wedding pictures and all those historic family photos. Photograph every room in the house, so as to record the superb furniture with which you have decorated, and while you’re at it, photograph all your jewelry and artwork, too. Now, store every JPEG and PDF to disk. Carbonite will automatically back them up.
Henceforth, it will also automatically back up every damnfool thing you write to disk. This is good, because it means you don’t have to rescue your computer from fire, wind, rain, or flood.
There really aren’t many documents whose originals you need to keep: probably your birth certificate (which you can replace) and the old family Bible are about it. Get a bank safe deposit box for those items, or else buy a truly fireproof safe to stash them and bolt it to the floor.
It probably would be good to keep a few gallons of water in the car, along with a hidden chunk of change or some cigarettes that can be used for barter, if you’re of the survivalist turn of mind.
There you go. Now every material thing you need is retrievable. The furniture and the tchotchkes are irrelevant. All you have to do is gather the living beings and get the hell out.
What would you grab on the way out of a burning building?
Sometimes I wonder just how smart it is to self-escrow funds to cover various large bills, such as homeowner’s insurance, property tax, and car insurance, and to sequester funds for emergencies. It could be that getting carried away with this strategy gives you too many cookie jars cluttering the financial countertop and two little in your main pot o’gold to maintain a lifestyle that you really could afford. Maybe.
Yesterday I was pondering how to get through the period when no paychecks are coming in: half of May and all of June. Next time the college pays me will be July 14.
This penurious period occurs, of course, just as utility bills are running up to their max—though we’ve been lucky this year with the weather. Right now, at five in the morning, it’s an incredible 62 degrees out there. It’s almost never that cool at this time of year. Still, I have had to run the air conditioning off and on, and so we can expect a bracing bill to arrive on the desk pretty quick. That, and the Mayo sent a bill for almost $400; apparently Medicare and Medigap covered rather little of the routine physical I got there a couple of months ago. And the Dog Chariot’s oil leak is getting worse—that’ll be another $200 or $300, not counting the $350 for a new timing belt. Plus the hateful palm trees have to be trimmed: yet another $350.
Anyway, while I was studying sources of funds to cover these expenses, it occurred to me that in fact I have more than enough cash in the bank to cover them. The problem is, most of it is dedicated to specific purposes. Videlicet:
Jeez. That feels like a ton of money to me. Maybe instead of having these funds scattered in four accounts (there’s also the joint account with M’hijito to cover the mortgage payments), maybe all the money should be piled in one account, from which all expenses are paid and the devil take the hindmost.
This would have the dual advantages of making me feel a lot less broke and of massively decomplicating bookkeeping.
On the other hand, it would also have the huge disadvantage of making me feel a lot less broke. Whenever I feel flush, I tend to think I can afford this little luxury and that little unnecessity. I would be buying clothes and furnishings and expensive take-out meals right and left if I thought I had 16 grand at my easy disposal.
The $9,300 in long-term living expenses is the relict of the $20,000 of incidental savings that was loafing in the bank at the time I was laid off the job. Since last fall, I’ve been drawing it down to live on, supplementing Social Security with enough to make ends meet during the times when no teaching income happens and in fact making it possible for me to dedicate all my net teaching pay to building up a large cushion in the joint mortgage-payment fund. At a spending rate of about $1090 a month, that fund will last until almost the end of 2013, at which time I’ll have to start taking drawdowns from retirement savings. That assumes that I’ll replenish it at the end of this summer with about $3,000 from unused teaching income, with about $2,500 from the final RASL payment that comes in next spring, and with 2012 and 2013 income tax refunds comparable to what came in last April. At any rate, sooner or later that fund will go away.
The tax and insurance fund is a manifestation of raw fear: I’m scared to death of not having enough to cover the property tax and homeowner’s insurance on my house. The apparent $2064 in available “daily living expenses” funds is an aspect of the same heebie-jeebies: $1,000 of that is reserved as a “cushion” to cover accidental overdrafts and emergency expenses; so really, only $1,064 is available to cover June expenses. That will jump by a thousand bucks when the Social Security check arrives…but not until mid-June.
The diddle-it-away fund is accrued at the rate of $200 a month and is dedicated to such things as clothing and little decorator items for the house. In fact, that’s where the money to pay for those car repairs will have to come from. As you can see, one truly major hit in the car repair department would do that little savings account in, which is one reason I’m thinking I should draw down some money from a brokerage account and buy a new vehicle. But I suppose that can be delayed until the major hit actually happens. The Sienna is almost worthless now, and so waiting until it doesn’t run anymore won’t make much difference in what I’ll have to pay for a new car.
But…what if I just paid these expenses out of one large fund until that fund disappeared, and then started drawing down enough from the IRAs and brokerage accounts to live on? Wouldn’t the result be the same as covering costs out of funds that are dedicated for living expenses, for small indulgences and small emergencies, and for tax and insurance? Wouldn’t life then be a great deal simpler?
I don’t know. Really, experience shows that, at least casa mia, spending expands to fill all available funds. If I didn’t have a clear vision of how much really had to be exempted from routine spending to cover taxes and insurance, I could easily blow that money at Pier One, Willams-Sonoma, and J. Jill. I would quickly go through the diddle-it-away savings, imagining that there was always at least a couple hundred bucks sitting around to spend on “wants,” not just “needs.”
But still. It is a nuisance. And having only enough in the month-to-month living expenses account to just cover the costs of running the house, buying groceries, and running the car does make me feel like I live on the edge of penury at all times.
That may not be a bad thing. When I can no longer teach, the fact is that the amount I can safely draw down from savings will, when combined with Social Security, just barely cover living expenses. Without the teaching income, drawdowns not only will have to cover my living expenses, they also will have to pay my portion of the mortgage. If I get used to living better now, having to pull back at that time, when medical bills will be even higher than they are now (they easily exceed the 7.5% of gross income required to make them tax deductible, and there’s nothing yet wrong with my health!), is likely to be very uncomfortable.
Better to stay accustomed to living very frugally because I imagine I don’t have enough than to hit a brick wall when the time comes that I really won’t have enough. That’s the reasoning, anyway.
At any rate, things are about to get a lot better, at least for the nonce.
Thanks to the two summer courses I managed to score, enough cash will flow in to cover base living expenses this summer. Last summer, I simply did not have enough to pay the bills without biting deeply into savings. This year, all that has changed.
Moving fall 2010 and spring 2011 teaching income into the joint mortgage-paying account, combined with negotiating a lower payment, created enough of a cushion in that cookie jar to cover an entire year of payments. Should anything happen to one of us, the other one will have plenty of time to figure out how to cope.
So, I can quit over-funding that account. This summer, none of the teaching income will go toward the mortgage, and in the fall, instead of moving everything I earn over there, I’ll start paying only my portion of the monthly mortgage bills, which is less than teaching pays (when it’s paying).
That will leave a little of each paycheck in my checking account. While it’s not a lot, it’s still enough to make things a lot less tight. And one month’s pay will handily cover the mortgage costs for the December-January winter break, when again no teaching money will be coming in.
This assumes no increase in teaching income—a safe assumption, since aduncts never get pay increases. Not bad, considering that thanks to increases in Medicare and Medigap premiums, my regular nondiscretionary bills have gone up by $194 a month.
If I put that extra money from teaching (net after paying the mortgage) into the long-term survival cookie jar, I could extend the life of the survival fund by about six and a half months (assuming I get the same number of courses next year as I’ve had this year). That would delay drawdowns from retirement savings well into 2013.
After that cookie jar is empty, if I’m still teaching I could use the extra teaching money to minimize the amount I’ll have to draw down from savings.
On the other hand… In 2013, I’ll be almost 70 years old. Not likely I’ll still be able to continue teaching then. I might make it through 2014, but it’s a long shot. The college doesn’t need to hire long-in-the-tooth retirees to staff its comp courses, given the hordes of unemployable English Ph.D.’s littering the landscape. Nor, probably, will I still be competent to ride herd on packs of 19-year-olds.
So, when I consider whether I could just use the extra money from teaching to engineer a slightly more generous lifestyle, I come right back to this hard fact: when the job ends, I’ll have to go back to living like an anchorite.
And if I’ve accustomed myself to a more generous lifestyle, that won’t be easy.
The cookie jars, in that light, serve a purpose: they ensure that I don’t get used to living in a style I can’t afford for long.
On Thursday Frugal Scholar expressed awe at the extent to which consumer prices have soared over a typical Boomer’s lifetime. And how! I can remember when you could buy a week’s worth of groceries for ten dollars.
She reproduces part of a Faux News squib showing how prices have (apparently) risen over the past thirty years.
Well…hmmm…. Basically all this says is that the relative value of currency changes over time.
My father once said that when he was a young man—that would have been in the mid-1930s—he earned $30 a month and lived well on it. The $1.41 FS cites would have been worth 9 cents in 1935. Depending on how you look at it, 1935’s $1.41 would be worth anything from $22.40 (consumer price index) to $282 (relative share of GDP) today.
Our problem today is that while prices are rising, income remains stagnant or even continues to fall through furloughing, pay cuts, and unemployment. Rising prices are not the issue. Employment is the issue.