Coffee heat rising

“Now Matters”: Balancing frugality with life

Trying again to get this post online. Looks like the WP glitch is now fixed; it was apparently a bug in Akismet. But now I’m having a heck of a time getting it to post at all. Have a bad feeling this thing has gone out to subscribers two or three times, but when and in what form, I don’t know. My apologies if you’ve received one or more versions of this already! 🙄

Spent the past hour or so stealing a few minutes to cruise my favorite blogs, which I’ve neglected shamelessly over the summer. At A Gai Shan Life, what should I come across but a rumination on the psychology of frugality—of the tendency to hoard, actually—and of Revanche’s fairly recent revelation:

…the idea that Now Matters has sunk in.

Yeah. Revanche attributes this insight to the maturing relationship with PiC, now her fiancé.

I’m slowly beginning to get the picture, too, though it may never come in clearly without some degree of “snow.”

LOL! Revanche describes not Seven Kinds of Ambiguity but Seven Kinds of Hoarding: saving the best food for last, so that you can enjoy the good stuff after you’ve polished off the required vegetables and stuff your mom made that you’d better not complain about. Racing through all your chores so as to collect up plenty of “free” (you thought) time. Stashing the candy, so you’d always have some for later. And of course, squirreling away every g.d. penny toward some uncertain “future.”

To this day, I always carve out the heart out of a piece of watermelon and set it aside, so as to eat the sweetest, most delicious part at my leisure: later. And indeed I do try to get all the sh!twork out of the way so as to have more time later, either to work on more productive things or just to loaf. As for money…well, you know, I am “a little funny about money.” 😉

I believe this tendency is in the genes. It’s hard-wired. I got mine from my father, and my poor son, who is even more miserly than I, inherited a double-whammy from his grand-dad and from me.

But like Revanche, I also am beginning to suspect that we need to invest something in the Here and Now, and we need to do it…well, now, not later.

I spend way, way too much time and energy depriving myself. As Frugal Scholar observes wryly about herself, “I do have a tendency to be a little too hair shirt in the frugality department.” She has decided to make a conscious effort to “loosen up,” as she puts it, by way of observing a few small milestones in life.

The women are right. It’s time to get a life. You can’t keep saving life for a rainy day.

In keeping with this impulse and my existing scheme to simplify my finances, I decided that I needed to find the single simplest way to regard income and outgo and then arrange the money management along those lines.

The biggest and best (I hope) manifestation of said impulse is that I’ve determined to stop worrying about every penny that comes and goes month by month—a stressful exercise, given the irregularity of adjunct income—and instead take a big-picture view of the budget and living expenses. Every winter break and all summer long, I chew my nails and tear my hair because I think “Oh GOD! I don’t have enough to pay the bills.”

Well, yes I do. Over the course of an entire year, I have more than enough to pay the bills. Between Social Security and the income from teaching three sections a semester, enough comes in to cover regular bills, pay for necessities, and leave a little to spare. You don’t see that when you look at month-to-month income. But if you back up and look at annual income, it comes into focus.

Videlicet: A year’s worth of income and outgo looks like this:
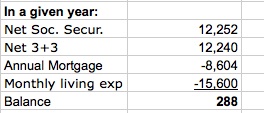
If I budget $1300 a month to supplement Social Security in covering discretionary and nondiscretionary costs, I just about break even, assuming I teach only three-and-three. But in fact, this year I’ve taught not six sections but nine, adding another $5,428 net to the bottom line. Thirteen hundred dollars is $200 a month more than I’ve been budgeting; it represents a more realistic figure in light of recent inflation. The income figures don’t include the $4,400 of RASL still owed to me in 2012, or the $2,000 or $3,000 income tax refund, or the annual American Express kickback, and so giving myself a little raise should be within reason.

Clearly, if I quit hoarding, I could afford to parcel out enough, month by month, to cover the bills. Occasionally there might even be enough to go out to dinner now and again.

One thing that’s made this not so obvious is that, in my terror that there just would not be enough to cover my share of the underwater mortgage on the downtown house, I started shoveling every penny of my salary directly into the joint account my son and I established to pay that mortgage. Over the summer, I had to stop doing that, because I needed the income from my summer classes to pay the exorbitant hot-weather utility bills. By the end of spring semester, however, I’d stashed enough in there to cover not only the three summer months but the entire year’s worth of mortgage payments.

This exercise made it clear that if I stopped doing that and instead transferred only enough to cover my part of the bargain, quite a bit of money would remain in my hands. Enough, indeed, to ensure that as long as I can dodder into a classroom, I’ll never have to draw down from retirement savings to put food on the table and a roof over my head.

Hmh.

If I were to put all my salary into Survival Savings (a money market account containing the fund of cash I had at the time I was laid off, which I’ve been slowly consuming by way of delaying drawdowns from IRAs and brokerage accounts), I could transfer $717 a month to the joint mortgage-paying account and $1300 to my checking account…and come out smelling like roses! Survival Savings has a balance of $9,464, so if this scheme begins on September 1, the numbers fall out like this:
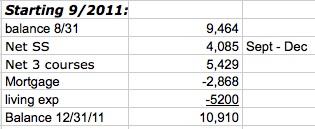
So what happens if I keep doing this in 2012? Again assuming I teach only three sections a semester, with no summer courses and no overload:
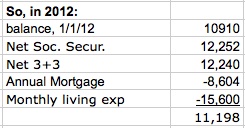
Yup, $288 to the good, not counting tax refund, 2012 RASL, the American Express card kickback, and the various other little windfalls that come my way. And that’s without having to teach in the summer! One summer course would cover emergency costs or keep me firmly in the black from now until Doomsday.

This zen-like strategy is made possible by the fact that I’d managed to squirrel away a substantial emergency fund while I was working full-time. After over 18 months, I still haven’t gone through it, despite a number of unpleasant financial surprises, like the $1500 on the teeth and the $800 on the car and the water bill of almost $200 and the power bill pushing $300.

So I can’t say that hoarding is a bad thing. Obviously, having built this stash by making myself think I was barely scraping by on $65,000 a year worked to my benefit.

However: it’s probably time to recognize that “Now Matters.”

Aborted Day…and night

Well, I see WordPress published that malformed post yesterday, despite my having taken it offline twice. Yuch. What an afternoon!

Hotter than the hubs of Hades here! Yesterday it was 110 and overcast.

I dread seeing another astronomical power bill next month. The AC has been pounding away day after day after day. Over July and August we’ve had two mornings, count’em, (2), when it was cool enough to shut the system off for a couple of hours. Otherwise, the system has ground along 24/7. And a couple of days I forgot to turn the thermostat back up to 80 in the morning—I no longer can tolerate having it much warmer than about 76 at night. At this age, when I can’t sleep at night I get sick. But after the last programmable thermostat produced not lower but higher bills, I had the AC guys put in a regular thermostat when they installed the new unit. This requires one to remember to turn it back up in the morning, another of those things you don’t do so well as age advances.

Pup was fairly good yesterday—at least I didn’t have to clean up any puddles. But during the hottest part of the day, when he and Cassie are crapped out on the floor like a couple of doggy corpses, I was working myself into a sweat struggling with the damn computer.

Ever since I upgraded to Worpress 3.2.1, the program has decided that it will engross the copy that follows an image into the caption. NOTHING seems to make it stop. It’s OK until I hit “preview” or “publish,” but that action seems to override the HTML clearly visible before then and move the content into the cutline. Sometimes entering a non-breaking line space after the code for the image & caption will work in a crude way, but it doesn’t work consistently. Tried to fix it in two browsers on two computers…finally had to give up. I guess the program is corrupted.

Fixing it is way, way beyond my abilities. Now I’ll have to hire someone to fix that.

Anybody got any nominations? With Mrs. Micah retired from that business, I haven’t a clue to who has that kind of skill.

So, until such time as I can hire someone to figure out how to deal with that, I guess no more images will be going up here.

M’hijito, continuing his after-hours project to escape to better employment, had a chemistry lab last night that went until 10:00 p.m. By evening, of course, Charley the Infant Golden Retriever was going strong. But since I’d wasted the entire flicking afternoon wrestling with WordPress, I had to grade 75 quizzes over my syllabi.

This, it develops, is the only way to get students to read your syllabus: give them an exam on it. And make them sign a form that swears they read and understood the syllabus, which you have to keep all semester because if you don’t they’ll try to claim they didn’t understand your due dates, the nature of your assignments, your “no late papers” policy, and the consequences of blatant plagiarism. As strategies go, it’s only mildly effective at making the students grasp what you’re saying, but it’s extremely effective at adding extra work to your day.

So while Charley was bouncing, I was trying to plod through scoring papers. That led to a fair amount of bouncing on top of Cassie, who was getting tired; running in and out to pee every 20 minutes or so; grabbing of verboten objects; and general frolicking. A couple of times I had to put him in his crate so I could focus on what I was doing, which didn’t help because he barks every minute he’s in there.

With M’hijito gone into the middle of the night, Charley’s visit here extended into Cassie’s dinner hour. Since Charley is a living vacuum cleaner that sucks up everything even vaguely resembling food (including pieces of paper, dead plant leaves, small insects, seeds, bark chips, sticks, and anything else residing on the ground, in the dishwasher, or inside a refrigerator), this posed a problem. Cassie gets real food: meat, veggies, and a starch. Charley finds this cuisine even more exciting than the exuberantly overpriced kibble he’s fed. And he’s already a third again as big as Cassie.

Okay, so I decide to snap a kiddie gate across the hallway with Cassie on the far side of it and then slip her food to her while he’s preoccupied with inhaling his kibble.

Not one of the brightest ideas ever to light up a marquee… Fazing one past Charley is not easy.

The instant he finished polishing his own dish to a high shine, he raced over to the gate to see what she was doing. There he became so exercised by the fact that she had FOOD that he jumped on the gate and knocked it over right on top of Cassie!

He dropped the gate on Cassie’s head, flipped the food dish completely upside down, and then landed on Cassie with so much force she couldn’t even bring herself to snap at him.

Oh god!

After that, he kept jumping on me while I tried to see if she was hurt—she kept licking her lips and I was afraid she’d broken a tooth. Finally I had to put her on the bed, which is so overly high that even I can barely climb into it. That kept him off her for a minute and her out of harm’s way until I could lock him in his crate, clean up the mess in the hall, and get back to inspect her more closely. She was OK, but she did seem a bit shaken up.

Charley continued active right up until the time M’hijito came over to pick him up, sometime after 10:00 p.m.

This made for a long day, since I’d had to be in Scottsdale for a business meeting at 7:00 in the morning.

That notwithstanding, I could NOT get to sleep! At 1:00 a.m. I sent an e-mail to La Maya to tell her I really didn’t want to leave the house at 6:00 a.m. to make the estate sale we were planning to visit—way to hell and gone back out in Scottsdale!

So of course she called me as dawned cracked.

Now I’ve gotta get up, feed Cassie before Charley shows up again, wash the sleep out of my eyes, and get ready to go teach another couple of classes. Thank god it’s Friday!!!

Urk!

Sorry, folks. Something must have corrupted when I upgraded (belatedly) WordPress. Just spent three hours trying to get a post online, and I can’t do it.

Soon as I can find someone techie enough to help figure out the problem, Funny will be back. Meanwhile, I’ve gotta get back to work!

Debt Consolidation: Proceed with Caution

Every time I get an offer from some feckless freelance writer trying to “give” me a “free” article plugging her customer, yet another debt consolidation service, I’m quietly amused. Well…no. I’m amazed: obviously some PF bloggers are publishing articles on debt consolidation that don’t give the whole story.

Debt consolidators negotiate with your creditors so that you make a single monthly payment to the consolidator, which then disburses small amounts and skims off a nice finance charge for itself. This may be useful for those who truly do not have the self-discipline to pay their bills and to snowflake them down with every small windfall that comes along. But for most people, it’s an expensive way to go. The FDIC notes that even though a consolidator may lower your monthly payments, the resulting plan will take longer to pay off your debts, and that the use of debt counseling is likely to show up on your credit report.

Some of these outfits are very smarmy. The Consumerist reports, for example, on the case of a “debt relief law firm” that collected $450 a month from a mark’s checking account, supposedly to pay down $23,000 worth of credit card debt. Not until the victim applied to rent an apartment did he discover the “debt relief” was actually theft, and that nary a dime had been paid toward his cards.

Some debt consolidators or alleged law firms charge excessive fees, often collected up front. These lead consumers even deeper into debt, failing to relieve their problems and even landing them in bankruptcy court. Although most debt consolidation companies claim to be nonprofits, they make a great deal of money at customers’ expense.

A number of years ago, while I was teaching at the Great Desert University’s westside campus and wishing I could earn more for less work, I applied for a job at a so-called nonprofit debt advising company. Starting pay for a job that required me to write lessons and conduct training in budgeting and personal finance was about $90,000—a phenomenal amount in a right-to-work state like Arizona. Various bonuses and perks were also promised. Companies don’t pay low-level executives that kind of money unless they’re making plenty of it.

Debt consolidation companies profit from their customers’ woes in a number of ways. One is simply to deduct a percentage of the payments passed along to creditors. Another is to engross one or two entire payments for “administrative costs,” dealing a blow to the borrower’s credit report when no  part of the payment ever reaches the creditors.

You don’t need a third party to settle your bills. Whatever these outfits do, you can do for yourself, and then some—at no extra cost.

• First, call your creditors and try to negotiate a better interest rate or payment plan. They don’t want you to default, because that costs them money. Many will work with you to pay down your debt.

If you’re behind on your payments because of a documented personal disaster, such as a health crisis or loss of a job, lenders will sometimes negotiate a reduced balance. This is far preferable for them than having you declare bankruptcy and pay them nothing.

• Next, always pay more than the minimum due. A minimum payment applies only about one or two percent toward the balance; your goal is to pay down the principal.

Most car loans and mortgages allow you to pay extra specifically toward principal. You may have to go in to the bank in person to accomplish this, but it’s worth the trip. The more of your money that goes toward the principal, the faster you pay down the debt.

• Establish a budget and stick to it. This budget should be designed to keep you from running up more debt. Stop charging stuff. Easier said than done, but that’s why you make a plan and stay with it.

• Create a sidestream income and pay all of the net proceeds toward the debt. If this means delivering pizzas after work in the evenings and on weekends, so be it. A side job is one of the most effective tools for paying down debt and building savings.

• Pay every extra penny that comes your way toward the debt. Got a rebate? Tax refund? A few bucks from a yard sale? Pay it straight into the debt, no matter how tiny it is. Every little bit helps. It’s surprising how quickly you can whittle down debt this way.

• Decide which works best for you psychologically: to attack the largest debt first or to go after the one with the largest interest rate. From a practical point of view, it’s usually best to get rid of high-interest debt first, since that costs you the most money over the long term. Some people, however, feel most oppressed by larger debts, even if the interest is low relative to a smaller debt.

By “larger,” I don’t mean your mortgage. This should be the last debt you decide to pay off. Get rid of revolving debt first. The small tax advantage given to mortgage holders defrays the actual cost of interest on these loans, and so the most urgent debt is represented by credit card and automobile loans.

• Pay off debts in an organized, systematic way. Establish a monthly amount you can disburse toward existing debts. Devote the largest part of it toward the account you decide to liquidate first, while paying something more than the minimum toward other debts. When that account is paid off, move your largest payment to the next account, and so on until, one after another, all the debts are settled.

None of it is rocket science. You don’t have to fork over any of your money to someone else to do these things. You can do them for yourself—for free!

If you still feel the need to talk with someone about your debt problems, the National Foundation for Credit Counseling can refer you to free or low-cost counseling and offers a number of consumer tools on its website.

Various household and other hints

Okay, so I was going to write a nice, solid PF piece with a fine political spin, but…it’s 110+ out there, I’ve run all over town, now have a couple of margaritas under my belt, and about all I’m up for is editing a detective novel (if that) and nattering on here. And hereabouts, about the best I can come up with is a few handy household hints.

Get gunk off wooden surfaces with mineral oil

The cheapest mineral oil in the world is to be had at Ikea. They call it Skydd; I call it Skkwsh.

Mineral oil (or baby oil, which is the same thing, but don’t put either of them on your baby) works miracles on soiled wood. Some people use it to polish furniture with oil finish; I personally don’t care much for that use, because it leaves an ever-so-slightly tacky film. However, it is the business for cleaning sticky stuff off utilitarian pieces of furniture and kitchen grease off the ledges and crannies of your kitchen cabinets.

This noon I made a run on Costco (’nother hint: never do that on Saturday!), where I finally brought myself to buy a folding table to hold the semi-permanent garage junk that has needed a home for a long time. Among other things, since time immemorial the shredder and the crockpot have each been perched on separate vintage cheap-wooden folding TV tables. Many’s the time I’ve thought that if I just had one of those large, cheapo work tables churches and schools always seem to have on hand, it could hold those two items plus a great deal of other in-the-way junk, and even more in-the-way junk could be stowed beneath it.

TV tables
Rescued vintage tables

Bringing this object—the folding utility table—into the garage liberated the two ancient TV tables. I brought them into the kitchen to clean them, it being way too hot in the garage for anything resembling physical work. They each had some sort of black greasy gunk, presumably well-aged drips from the crockpot seasoned with dust-storm residue.  Wiping them off with a wet paper towel did nothing to dislodge the black greasy spots.

mirror hiding cheap ugly tables
Best to hide the things...

But: rubbing a little mineral oil into the top of the table, letting it sit for a minute, and then wiping it vigorously off removed the stuff without a whimper. Cut about 15 years off the crotchety old tables’ apparent age, too. Sure would be nice if the gunk would have the same effect on the aged human face.

Don’t even think of trying that. It’s toxic.

Moving on…

Store household cleaners in plastic tubs…and be smart about it!

Said garage is lined with storage cabinets, and one of the shelves of said storage cabinets holds my various lifetime supplies of household chemicals. Among those chemicals one could find a couple of bottles of ammonia, which I use to make a DIY version of Windex glass cleaner.

I keep these things, for convenience, in small plastic bins, the sort of things that used to be sold as dishwashing pans. They make it possible to slide out a whole slew of bottles and cans, rather than having to stick my head into the cabinet and shuffle through a bunch of containers in the dark

Welp, turns out this habit has another benefit: if one of those containers leaks, the plastic bin collects and contains the liquid, keeping it from creating a gawdawful mess all over your cabinetry!

Yesterday afternoon preparatory to washing the Arcadia doors, I pulled out a bottle of ammonia, therewith to whip up some more glass & tile cleaner…only to have it splash on my bare feet! The damn plastic bottle had developed a leak!

Pulled out the plastic bin, hauled out and rinsed its contents. Godlmighty but in there were not one but two unopened bottles of Clorox toilet cleaner, a substance liberally laced with chlorine bleach. As we know,

ammonia + chlorine bleach = death.

Mercifully, the toilet-cleaner plastic bottles were not breached. I carried them into the backyard anyway.And the particleboard shelves were unruined—they would have been trashed if ammonia had been quietly dripping onto them for God only knows how long. So:

Item: Storing bottles of household chemicals in plastic bins is a good idea. But…

Item: Do not store products that contain bleach in the same plastic bin with products that contain ammonia!

Get gunk off tile grout

half-cleaned tiles
Before in the foreground; cleaned toward the top

Satan and Proserpine, previous owners of the Funny Farm, laid a bunch of tiles down in the living room, hall, kitchen, and dining room, all by their little selves. My tile dude said they did a good job of it, but like moi was mystified at the reason for their having slathered the grout with off-white “sealer” that really is nothing more than a type of latex paint.

Now…what happens to white grout over time?

Yeah. It collects dirt and turns…well, dirt-colored.

Same thing happens to fake white grout created by painting real grout with latex “sealer”: over time, the joints in S & P’s tiles (hm. Hadn’t thought of that confluence. Was the latest market crash and rape of the Baby Boom’s savings caused by Satan and Proserpine themselves?) …Yes, the joints in the tiles had become grody, to put it kindly. Yesterday with Pup out of my hair and all of next semester’s courses designed and posted online, I took it upon myself to do some serious cleaning.

What should I find when I emptied out the plastic bin into which a bottle of ammonia had slowly been leaking but a box of Mr. Clean Magic Eraser wall cleaner knockoffs from Target!

Recalling that these strange chemical sponges do a great job of cleaning the grout between Mexican tiles on the countertop, I decided to try them on the fake grout paint stuff on the floor.

Amazing!

clean tile grout
Totally after

It made a huge difference: so huge that where I accidentally  missed a line of grout, it jumps right out at me. The tiles look almost as bright and clean as they did when I moved in here, shortly after those two painted the stuff on all the grout in the house.

The box contained four pieces of the stuff, which dissolves annoyingly as you scrub with it. These cleaned the kitchen, dining room, and the endless hall floors. Next weekend I’ll have to buy another box of the stuff from Tar-Zhay and do the living room. Very, very effective.

Make magnetic fridge notepad and pencil

You’ve seen those cutesie magnetized notepads with stick-to-the-fridge coordinating pencils and ballpoints? Of course, being a little funny about money yourself, you’re too cheap to spend the stupid amounts of money these pieces of kitsch cost, even though you can imagine the handiness of having a pad of paper hanging from the refrigerator, there to post stuff you’ve run out of.

Well, cheap yourself out of these things no longer!

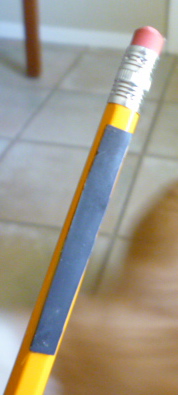
First, get yourself an old-fashioned yellow pencil, the kind that’s milled with six flat sides. Cut off a two-inch-long (or so) strip of rubbery stuff the width of one of these sides. Remove the protective backing and stick it onto the pencil, just below the eraser.

Voilà! Now you have a pencil that will stick on the fridge. And I suppose you see the rest of this coming, eh?

Now get yourself a small yellow pad, 5 x 8 inches. These are available in lifetime supplies at my favorite purveyor of middle-class goods, Costco.

At any good craft store (such as Michael’s or even…yes! Home Depot) you can find magnetized sheets of bendy rubbery stuff, which you can cut with scissors.

The rubbery stuff has a stick-on backing, which is and is not sufficient for our purposes.

Cut off several more fairly large pieces of rubberized stuff, so that you can glue at least a couple on the cardboard backside of the yellow pad. It will probably take more than one. Depending on the brand of magnetic rubbery stuff, I’ve had it take two or three pieces to hold up a mini-yellow pad.

Do not buy a lifetime supply of magnetic rubbery stuff! It’s ridiculously easy to reuse this stuff. When you run out of paper, or when you’ve sharpened your pencil down to where its magnetic holder resides, simply pull off the rubbery stuff and glue it, using some Elmer’s or carpenter’s glue, onto a new pencil or pad. It lasts forever.

And there you are: A kewl yellow pad and pencil, hanging at your disposal on the fridge at all times!


Out and About on the Web

And if you’ve done all these things and still find yourself at loose ends, pass some time at a few friends’ websites:

Okay, this is one you have to follow. First, Mrs. Accountability flies into a tit when she discovers Wells Fargo is about to start gouging her for the privilege of using her money to make a profit. Like any sane PF consumer, she decides it’s time to find someplace else to do her banking. Then she realizes what’s involved in this venture and makes an executive decision.

Guess I’m not the only one who loved (or at least got excited about) this post from Nicole and Maggie at Grumpy Rumblings of the Untenured on passing judgment about other people based on their personal pastimes. It’s a great post, and the comments come up to the same standard. Hm. You know, I think this may be one of the truly great personal blogs out there, right up there with Donna Freedman’s Surviving and Thriving.

Speaking of the which, I don’t know how that woman manages to say so much in so few words.

Frugal Scholar’s post on the counterproductiveness of saving is well said.

In the earning, planning, and saving department, Evan has a few well-placed observations over at My Journey to Millions.

And along those lines, FMF offers some really startling insights at Free Money Finance. This is quite a piece of writing. If you’re still in your earning years, you need to read it. If you’re not but have children or friends who are, pass it along.

But in the same department, SVB over at Silicon Valley Blog brings up an entirely new set of questions about planning for lifetime savings and retirement.

Money Beagle contemplates the value of an insurance agent.

Afford Anything remarks on the spreading tendency to install valet parking…everywhere!

Onward!

Image (other than Funny’s): “All is Vanity” by C. Allan Gilbert. Life, death, and meaning of existence are intertwined. (Woman gazing into boudoir mirror forms shape of skull.) Public Domain.

Two-day break…sorta

So the 7:00 a.m. English 102 class ended on Thursday. Because I’d asked them to turn their last, horrendous 2,500-word essays in on Monday, I managed to post semester grades Thursday afternoon.

Friday was largely occupied with cleaning up the 102 website, writing a complicated addendum to the syllabus to handle the changes inflicted at the last minute when the library announced, two working days before fall classes begin, that it’s canceling in-class literacy instruction, and arranging to get still more pieces of paper printed. So by about 7:00 p.m. last night, I thought the summer courses were finally shoveled off my desk.

Not quite: just noticed I failed to delete drafts and peer reviews from the site. So now the computer grinds away, trying to delete 350 items one “page” at a time. Ugh.

Oh hell. For some reason, WordPress just deleted everything I wrote in this post. Having spent an hour writing all that stuff, I am NOT gonna write it again. Gotta get to cleaning this filthy house: last week’s dust storm again covered the floor with grit, and a week of doggy day care didn’t help things.

Back on Monday!