Coffee heat rising

What Price Gasoline?

Like everyone else in town, I’ve been putting off buying gas until the last possible minute. Wednesday evening, the Dog Chariot had what looked like a quarter of a tank left. Figured I could get to my Scottsdale breakfast meeting and back to the in-town Costco (cheapest known source of fuel in the city), and so at 6:30 headed east. Interminably east.

By the time I got to lovely mid-town Scottsdale, the gas gauge registered 1/8 of a tank. But the road was slightly inclined, and sometimes (I hoped) the unlevel miniscus in the tank would warp the reading. As I turned onto Scottsdale Road, I noticed a Sinclair station in the AJ’s shopping center at Lincoln and Scottsdale.

Once sprung from the breakfast meeting, I stopped in to pick up a gallon (worth 18 miles), which I knew would carry me into town, where I could fill up at the ghetto Costco.

Pulled up to the pump behind some rich guy who wasn’t even paying attention to how much gas was blasting into his tank, viewed the amazing prices (in Scottsdale gas station owners are not allowed to flaunt their prices with gigantamous roadside signs), backed out, and drove away.

I should’ve known. Sinclair????? There are no Sinclair stations in Arizona. This is some sort of artifact. And what do artifacts cost?

$4.50 a gallon, that’s what artifacts cost.

{gulp!} Could I be reading that right? Surely not. But I wasn’t sticking around to find out.

Drove west, drove west, drove west, drove…until the red idiot light came on, along about 36th street. Spotted a Chevron station at 16th street. Darted in and pumped 1.5 gallons of $3.79 gas. This would suffice to reach the pore folks’ neighborhood.

Drove south drove south drove south drove west some more.

At last I reach familiar territory and whip into the Costco gas station off 19th Avenue and Bethany Home, the lot nearly empty because the store isn’t open at this hour. Usually the line is halfway out to the road.

Hot dang: $3.67!

So it was that, compared to what I would’ve paid if I’d lived in lovely uptown Scottsdale, I saved $12.03 on 14.5 gallons of red-blooded Arabian gasoline.

I reflect: If I had a car that made 35 mpg, such as the Hyundai Sonata, I’d only have to fill up once a month. That would save me $58.72 a month.

Maybe it’s time to trade in the Dog Chariot. Whiz-Bang Financial Manager, having calculated my Vanguard Funds’ cost basis according to my father’s date of death, says I should have to pay zero taxes on the short-term corporate bond fund that was my car-purchase savings while I had a job. He thinks it’s stupid to pay $350 for a new timing belt on an 11-year-old junker (he predicts + + + operating costs). Accountant thinks it’s a toss-up: buy, don’t buy, do what you want…probably doesn’t make much long-term difference.

Hmmm… $58.72 a month = $704.64 a year saved on gasoline.

Cost of new Sonata less trade-in on the junk = around $20,000; 4% of twenty grand (allowable drawdown from invested retirement savings) = $800. Not exactly a toss-up, unless you factor in the $350 for the timing belt plus God only knows how much for other repairs.

Cost of 2011 second-hand Sonata through the credit union’s car-buying service, 22,000 miles: $19,900 – $3,000 = $16,990; 4% of $16,990 = $680. Very probably a positive. It’s not the color I want. It doesn’t have the interior trim I covet. But…there it is.

Still thinking…

Images:

Sinclair Oil advertisement, Menard, Texas.Billy Hathorn. Creative Commons Attribution-Share Alike 3.0 Unported license.

Hyundai Sonata. Shamelessly ripped off the Arizona State Credit Union‘s car-buying site. Click on this and a whole bouquet of pop-unders will populate your computer monitor.
Medicare Bills: OMG!

Anybody who thinks Medicare is some sort of a bargain and that all us old folks are sucking off the public teat either doesn’t know what he’s talking about or is just batshit crazy.

Just paid my annual Medigap premium: it rose by $277! That was after the Part D, which covers nothing because I don’t take any meds, went up by $60 a year. Part D is provided by a private insurer, but Medicare recipients are required to subscribe to it on pain of a penalty that amounts to a heavy, recurring fine. Part B also rose this year, but Social Security rises to cover Part B increases even in years when there’s no COLA increase (we’re now in the second year with no Social Security COLA, because after all there’s no inflation. :roll:).

Not anticipating such a large jack-up, I failed to self-escrow enough to cover the increase, so I had to raid my regular savings to pay the bill. Another two months with no clothes! Guess I’ll be wearing black Costco jeans all summer. Damn!

Medicare now costs some 15 times what I was paying for similar coverage at the Great Desert University. And of course it doesn’t cover everything. The Mayo keeps sending me incomprehensible bills, and the various Medicare providers keep sending me incomprehensible statements. Piles of paper are swelling my file folders, and I have no idea what any of it means…it’s just impossible to parse it out.

What this means is that I have no idea what I need to pay my doctors out of pocket. And that means I can’t really ever get out of debt to them, because I don’t know what to pay. Even if I could afford to do so, I can’t pay the full amount of each statement and then pocket the amounts coming in from Medicare/Medigap, because the clinic’s bills don’t reflect all the pending charges; if I spend the Medicare checks on groceries, I won’t have anything to cover the new little surprises that keep coming in the mail.

Complicating matters, Medicare will not pay the Mayo directly, advertisements to the contrary notwithstanding. The Part B coverage is supposed to direct-deposit payments to the Mayo, but for some reason because it’s the Mayo they won’t do that. Hell, no! Instead, they dribble out checks to me by snail-mail, which I have to deposit and then disburse to the Mayo myself.

Needless to say, the potential for snafu is huge. There’s always the chance that some check will be lost in the mail or in the piles of paper in my house—because a blizzard of trash paper is always coming in from these insurance companies, it’s easy to lose an envelope with an actual check in it.

Mercifully, I can now scan checks and deposit them electronically. It’s almost as much of a nuisance as physically driving to the credit union, because my scanner is excruciatingly slow. And of course, it draws so much memory or power or whatever it’s doing, I can’t do anything else on my computer while I’m waiting for it to plod through the process. The CU’s system won’t accept color scans, but my scanner defaults to color. Sometimes even when I set it to scan greyscale, it defaults right back to color. So then I have to do the whole scan over again. One time it took over half an hour just to scan in one check so the system would take it—I could have traipsed to the credit union on the way home from campus in that time!

Dealing with this bureaucratic BS is a difficult nuisance now, while I have most of my marbles. I can’t even begin to imagine how the elderly frail cope with this tsunami of confusing, complicated, demanding crapola. If you don’t have someone in your life to help out with it, you’re SOL. And you can be sure you’re getting ripped off seven ways from Sunday.

There’s just no excuse for America’s healthcare system.

Blackboard: Always Leave ’Em Tearing Their Hair…

Un. Freaking. Believable.

But maybe not. Maybe I should’ve known I wasn’t gonna escape from Blackboard without one final pain in the butt.

One hundred thousand words of student writing was to cross my transom come Tuesday. A few eager beavers turned in their gigantic final papers over the weekend, so on Monday I read the early entrants in the course’s final steeplechase.

Blackboard, the bloatware that passes for the course management software favored by the local community college district, should add up each student’s points and then tell you what percentage of the semester’s total available points these figures represent. In the past, it has done so quietly and efficiently, much speeding the process of posting final grades.

So Monday I enter an A-minus (90 points) for a certain student.

Blackboard awards him a final score of 138.6 percent.

No kidding? This is a B-minus student at best. He’s racked up no extra-credit points, and he has missed 50-point assignments. How could he possibly have accumulated more than the total points available?

Whip out my calculator and discover that he in fact has captured 79 percent of the total available points.

Hm. This would explain why one of our brighter lightbulbs, one who indeed did perform a bunch of extra credit and who turned in his final paper even earlier, managed to rack up a score of 148 percent.

Manually recalculate his grade: 95 percent.

Enter a few theoretical final paper scores in other students’ rows. When we say all our children are above average, we’re not kidding!

Try to figure out what the problem is. I must have made some mistake, but I’ll be damned if I can find it. All the columns’ settings are the same, and as far as I can tell, they’re all correct.

Finally have to concede that the only way to figure their final scores without having to punch every number (that would be hundreds of numbers!) into a calculator is to build an Excel spreadsheet that works and import the data into that. Make it two spreadsheets—one for each of the composition sections.

This was not a difficult job, but it was tedious, made more so by the fact that the array of assignments differed slightly between the two sections, so I had to build two separate spreadsheets. Then I had to send out announcements and e-mails to all students in each section explaining why they couldn’t rely on their Blackboard “My Grades” function, how I would be figuring their grades, how to calculate their own grades. Of course this generated a flurry of e-mails from students in High Obsessive Gear. So I got to kill Monday evening farting around with still MORE unnecessary extra work generated by Blackboard.

This will be the last assignment I ever enter in a Blackboard spreadsheet. Starting with the summer term, my classes are moving over to sites created in WordPress.com. Communication will happen through that site and through G-mail accounts dedicated exclusively to specific courses, so that I don’t have to sift through all the junk mail that comes in from the district and two campuses to find messages from students. Grades will be kept in spreadsheets very like the ones I built Monday night. I may put them up on Google Docs, so I can access them from whatever computer I happen to be using. I’ll give students blank, formatted spreadsheets so they can enter their own grades and view their accumulating points and percentages.

Wouldn’t you know Blackboard would pull this stunt on the way out?

Small Frugalities, Small Chintzinesses?

Chintzinesses? How d’you like that word? I can’t think of a word parallel to “frugality” (n) that means “an act of cheapskatishness.” Nor can I think of a word meaning “the state of being a cheapskate.” Cheapskatitude?

At any rate, our subject is that perennial favorite: When does one cross the line from frugality to chintziness?

This weekend I happened to mention to M’hijito that when La Maya and I were out and about in pursuit of a distant estate sale, we stopped at a Starbucks, where I ordered a café Americano. He allowed as how the only way to get a decent cup of black coffee at that chain is to ask for the café Americano, as their ordinary drip coffee is battery acid, fit for nothing other than as a cheap medium for sugar, artificially flavored syrup, and milk or cream. Café Americano is dilute espresso. The reason it tastes better than Starbucks’s normal drip coffee is that espresso beans are higher quality than the schlock used to make the battery acid.

Then he remarked that he highly resented paying $4.30 for an iced coffee (the price being the same, whether you take your coffee hot or cold).

This remark caused me to reflect that yes, I had paid $4.30 for a medium-sized café Americano. Uhm…yes. Four dollars and thirty cents for a cup of coffee.

I mean, really. Four and a half bucks for 50 cents worth of ingredients and three minutes’ worth of a minimum-wage slave’s time? Does that make sense?

Well, it wasn’t the coffee we were buying so much as the moment to pause and socialize—and to get someone else to provide the social lubricant of a hot, caffeine-laced beverage. Could we have gone to one of our homes and fixed our own coffee, saving about $8 on the $8.60 the two of us spent at Starbucks? Of course. But it wouldn’t have been the same.

As a practical matter, once we got back to our neighborhood, we each would have figured it was time to go on about our daily business, and we probably wouldn’t have taken the time  to fix coffee. Or, if we had, we would have diddled away too much time in one living room or the other, and then we each would have felt put upon by the many tasks that awaited us in our respective days.

Sometimes I wonder if I’m not way too tight about things like this.

Take, for example, the cell phone issue. I’ve resisted getting a cell phone because I think I already spend too much on connectivity—$78 a month to keep my computer online and the landlines running is too darned much for phone service. More to the point, in my mind I can’t afford another $80 to $120 for an electronic tether.

Really?

My gross income, if you include the $1,025/month coming from savings, is $7,000 a year more than my son’s. If, rather than setting aside my entire teaching salary, I self-escrowed only enough to cover my share of the mortgage (and let the future take care of itself, even that means the future surely will include a foreclosure), what remains of my gross would only be about $1,525 less than my son earns.

And he can afford an iPhone. Keeping that thing online costs $120 a month!

So why couldn’t I afford, say, a Droid, at $80/month to Verizon?

Surely I could at least afford an iPad. That costs only $15 or $25 to connect. And despite the fact that the way-cool iPad isn’t designed as a phone, an easily accessible app will give you free phone service through the thing! With that, I could have my cake and eat it, too: get the coveted electronic gadget, use it as a cell, and not even have to cancel the landline.

M’hijito never has paid for a land line. He uses only his cell phone. IMHO, this is something of an inconvenience, because he’s always misplacing the thing and not answering calls when he can’t find the phone.

SDXB recently canceled his land line service. He also is now using a cell only. He claims he doesn’t lose it because he carries it around with him everywhere, and because he has a single place in the house to keep it when he’s not using it.

Right. I had a single place to keep the $725 pair of glasses I just lost.

Still. If I canceled the landline, all that would remain of the Cox bill would be $50 a month for the computer connection (SDXB says he’s only paying $30 a month, presumably because he has a slower service).

My S-corp could pay for the iPad connection to AT&T—it’s only about $25 a month. If I could use that with Google’s Talkatone to make free phone calls, the worry about calling for help when my car craps out on the freeway would go away. And that concern is the only real reason I want a cell phone. If the S-corp were footing the bill for the mobile phone connection, there would really be no reason to cancel the land line, which allows for a telephone in every room in the house—no chasing around every time the phone jangles.

Canceling the landlines and having the S-Corp pay for the iPad would cut my personal nondiscretionary budget by almost $30 a month.

Here’s the question: Am I frugal or am I cheap to keep resisting the mobile phone?

For that matter, is it frugal or is it cheap to consider adapting the reasonably priced iPad (reasonably priced considering what it is!) for use with Google’s free voice app and calling that a “cell phone”?

Is it frugal or is it cheap to consider canceling the land line if I could get the iPad to actually function as a telephone?

Is it frugal or is it cheap to think coffee should be purchased at Starbuck’s only on special occasions—or preferably, not at all?

Roundup: Summer’s Here Edition

w00t! The pool is finally warm enough to swim in—just! Took the plunge this afternoon. It’s wonderful.

Yesterday a choir friend threw a Cinco de Mayo party at her home. After a warm day, the evening was cool and lovely, perfect for outdoor dining, socializing, and karaoke.

Two percent humidity on a 100-degree day means the half-cup of tea you left in the car evaporates to a dry, brown stain overnight!

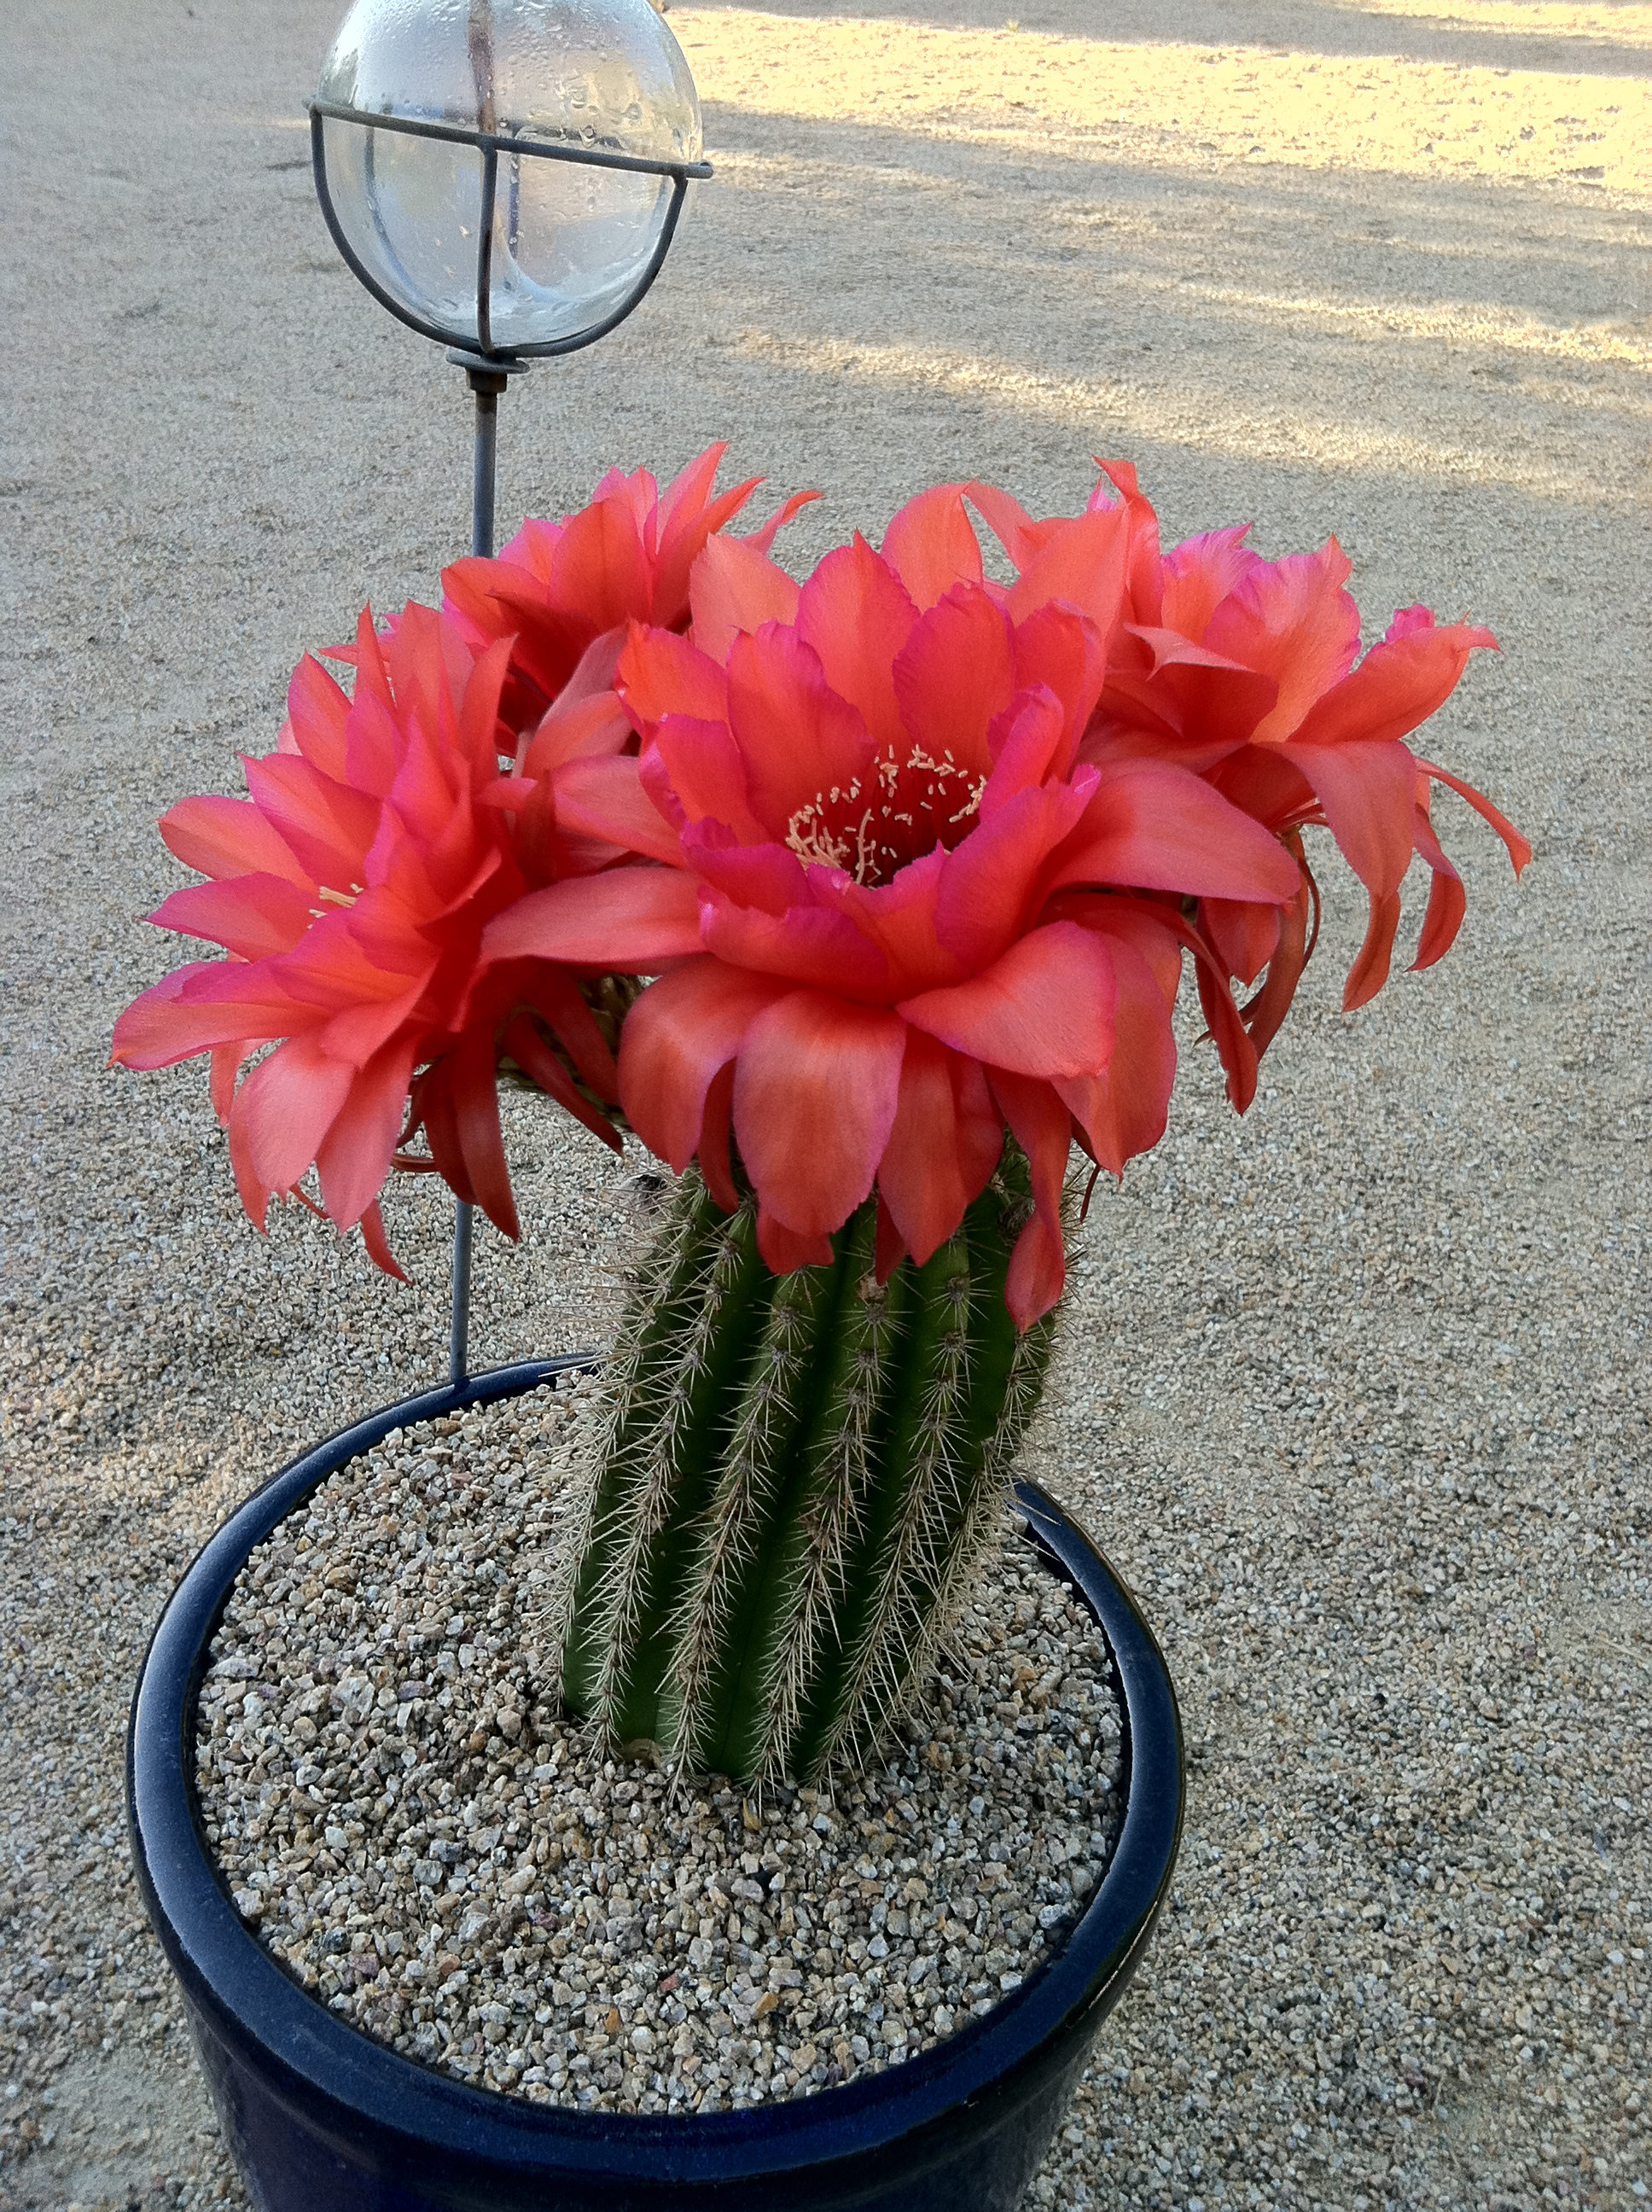
And this incredible thing blossomed in M’jihito’s backyard:

Out and about on the Net, various entertainments continue. Revanche, traveling to Thailand, reflects on the permutations of romance.

Mrs. Accountability considers the costs of sending flowers on Mother’s Day. Yipe!

Know what a perpetual income machine is? Sounds good, doesn’t it… Over at My Journey to Millions, Evan explains and describes his.

Money Beagle has a nice rumination on the Bin Laden assassination. Good riddance to that bad rubbish!

The Frugal Scholar household, having retrieved her daughter safe and sound from Tuscaloosa and having seen Frugal Son graduate from college, is converting Son’s bedroom into a staging area for donations to the tornado-ravaged city.

Donna Freedman reflects humorously on the urban farming phenomenon.

Bucksome Boomer speaks to the reasons young people are moving away from California in droves.

Budgeting in the Fun Stuff publishes a guest post by Jacob of My Personal Finance Journey, comparing costs between Petsmart and Petco.

At the Digerati Life, SVB guest blogger Paid Twice delivers a pep talk on getting out of debt.

Mrs. Money, over at The Ultimate Money Blog, reflects on paperless billing.

Money Crush proprietor Jackie has had a nice run of short, thoughtful pieces in the past week or so. The latest offers insight on the difference between thrifty and cheap.

Bargain Babe’s latest post lists a slew of awesome bargains, among them free movie rentals, a half-price Starbuck’s drink, and a deal at Marie Callendar’s. Many of these expire soon, so hurry on over there to see what you can score!

Here’s a rather charming blog I stumbled across the other day, which you might enjoy visiting: Walkin’ in High Cotton.

The New York Times takes on the question of whether a college education is all it’s cracked up to be.

And AARP Magazine publishes an excellent article on marketing psychology.

Love Drop Update

Love Drop, the terrific blogger’s combine whose goal is to bring relief and caring to families in dire need, reports that the April Love Drop aided the Kahlens, who have suffered from the economic collapse and whose daughter suffers a hereditary malady. Take a look at the fantastic array of money and gifts showered on this deserving family.

May’s Love Drop family is the Stalnakers, generous community-minded Louisianans going through hard times.

Want to help?  Here are three ways you can participate:

Help them get a car!  The #1 goal is to give them a reliable used car in decent working order. If you have any leads, discounts, or connections in this area, please email Love Drop and let them know.

Give $1.00. This money will help get them back on their feet, and relieve some financial burden. Every dollar counts!

Give a gift or service. Gift cards are always helpful. Places like Target, Wal-mart, restaurants, etc would definitely help them out. Services too—especially those you can offer yourselves, or from your company.

And if you have a site of your own, don’t fail to blog about this month’s family in need!