So I’m driving home from campus, a-listenin’ to the radio. Got a fistful of errands to run before I can come to light back at the Funny Farm, so I need the radio to keep me company for a while. Seemed like half the day that NPR had been moaning on while Rome burned (again!).
Enough, already, of the stürm und drang! How much of this can any one human being listen to without losing its mind? A click of the button sent the radio dial surfing across the airwaves to the cowboys. The Cistern (that’s “City Western”) station tuned in just in time for the start of this:
And you thought cowboys have no sense of humor?
Y’all come over for some of that home-made wine, y’hear? We’ll be needing it…
Didn’t do much today but am just about wiped out with exhaustion. Compiled the Best of Money Carnival and scheduled it, but it was halfway done before this. Went with M’hijito to return the redundant dog crate to Walmart (His Maleness to haul the damn thing), there to collect a $90 refund. Ran over to Ace to pick up some new Danish oil with which to repair the puppy scratches on the kitchen cabinetry; got it home before I realized it was “walnut” stained; drove back through the heat-crazed traffic to get the “golden oak” flavor. Did the laundry, including the sheets. Fooled with the pool some more. Did battle with a difficult student who deserves a C-minus, is getting a B, and believes she should have an A.
Never did get around to cleaning house: too hot to function. Decided to put the puppy crate in a cooler part of the house, since the area where I’d like to locate Doggy Central is significantly warmer than any other rooms. Put the Navajo rug back on the wall where Pup tried to pull it down. Watered plants.
Finished off the day responding to a student who got a zero on the last paper (for not having done the assignment in spite having been warned at the draft stage) and threatened to go to the chair. Forthwith this development was topped off with the discovery that the washer overflowed and flooded the garage. Just spent a half-hour sweeping a lake down the driveway.
More gawdawful pretend news on the idiot box now, at 10:00 p.m.
Am I the only human in the country who’s bored stupid with the “what does the S&P credit downgrade mean for YOU?” pretend-news stories?
The answer:
Nothing.
There’s not a damn thing any of us can do about it.
• Are we going to lose our shirts? Not likely: our shirts are already lost. You can’t lose a shirt you don’t have anymore.
• So our credit-card interest is going to go up? This matters to people who can’t afford to charge anything on credit cards in the first place?
• Our variable-rate mortgages are going up? How many more houses will go into foreclosure? Does this change things one way or the other? Real estate is already so profoundly trashed that a few more hundred thousand foreclosures will mean nothing.
• Our student loan interest is going up? Will this make any difference to those of us who are going back to school because we can’t get work? Will it change the plans of college kids who couldn’t get jobs if they tried?
Speaking of going back to school to retool for new work that represents underemployment, I heard from a client who’s a medical doctor in response to my questions to him about medical transcription as a possible new income generator.
He said that indeed a medical transcriptionist can make a decent wage. And while it’s true some of the work is being offshored, most jobs are still here in the U.S. But, says he, “The job is tedious and low intellectual in my opinion. You and Tina are way overqualified for the job. I hope you can find a better option to use your talents.”
So true. However, there seem to be no better options. Tina’s already waiting tables two or three evenings a week, after she gets off her full-time editing job. I’m a little old for that kind of strenuous work, though I suppose I could clean house, another trade that pays more than I’m earning at adjunct teaching. Exactly how “intellectual” it really is to teach people who think Arizona is a “Great Plans” state, Wisconsin is a Rocky Mountain state, and World War I happened in the 19th century remains to be seen. And as for tedious: dealing with people who don’t pay attention in class, refuse to address the assignment, and then threaten to complain to your boss when you flunk them…that defines tedious.
If I can earn the same or more transcribing doctors’ case notes, actually get paid for all the hours I work, engineer an income all 12 months of the year, and not have to put up with a lot of bullshit, I’ll take a new form of unintellectual tedium.
Looks like we may have found JackDaniels’s real name: as he was clambering around the backyard yesterday it struck me that his name is Charley.
Asked M’hijito about that idea. He seemed to like it; said he wasn’t crazy about “Jack” because it’s too close to “Jake,” the name of his childhood pet.
Annoyingly enough, I’ve taken to calling my son’s dog, tentatively named “Jack,” by my idea of his name: jackdaniels.
My poor son. Will there ever be any relief for him?
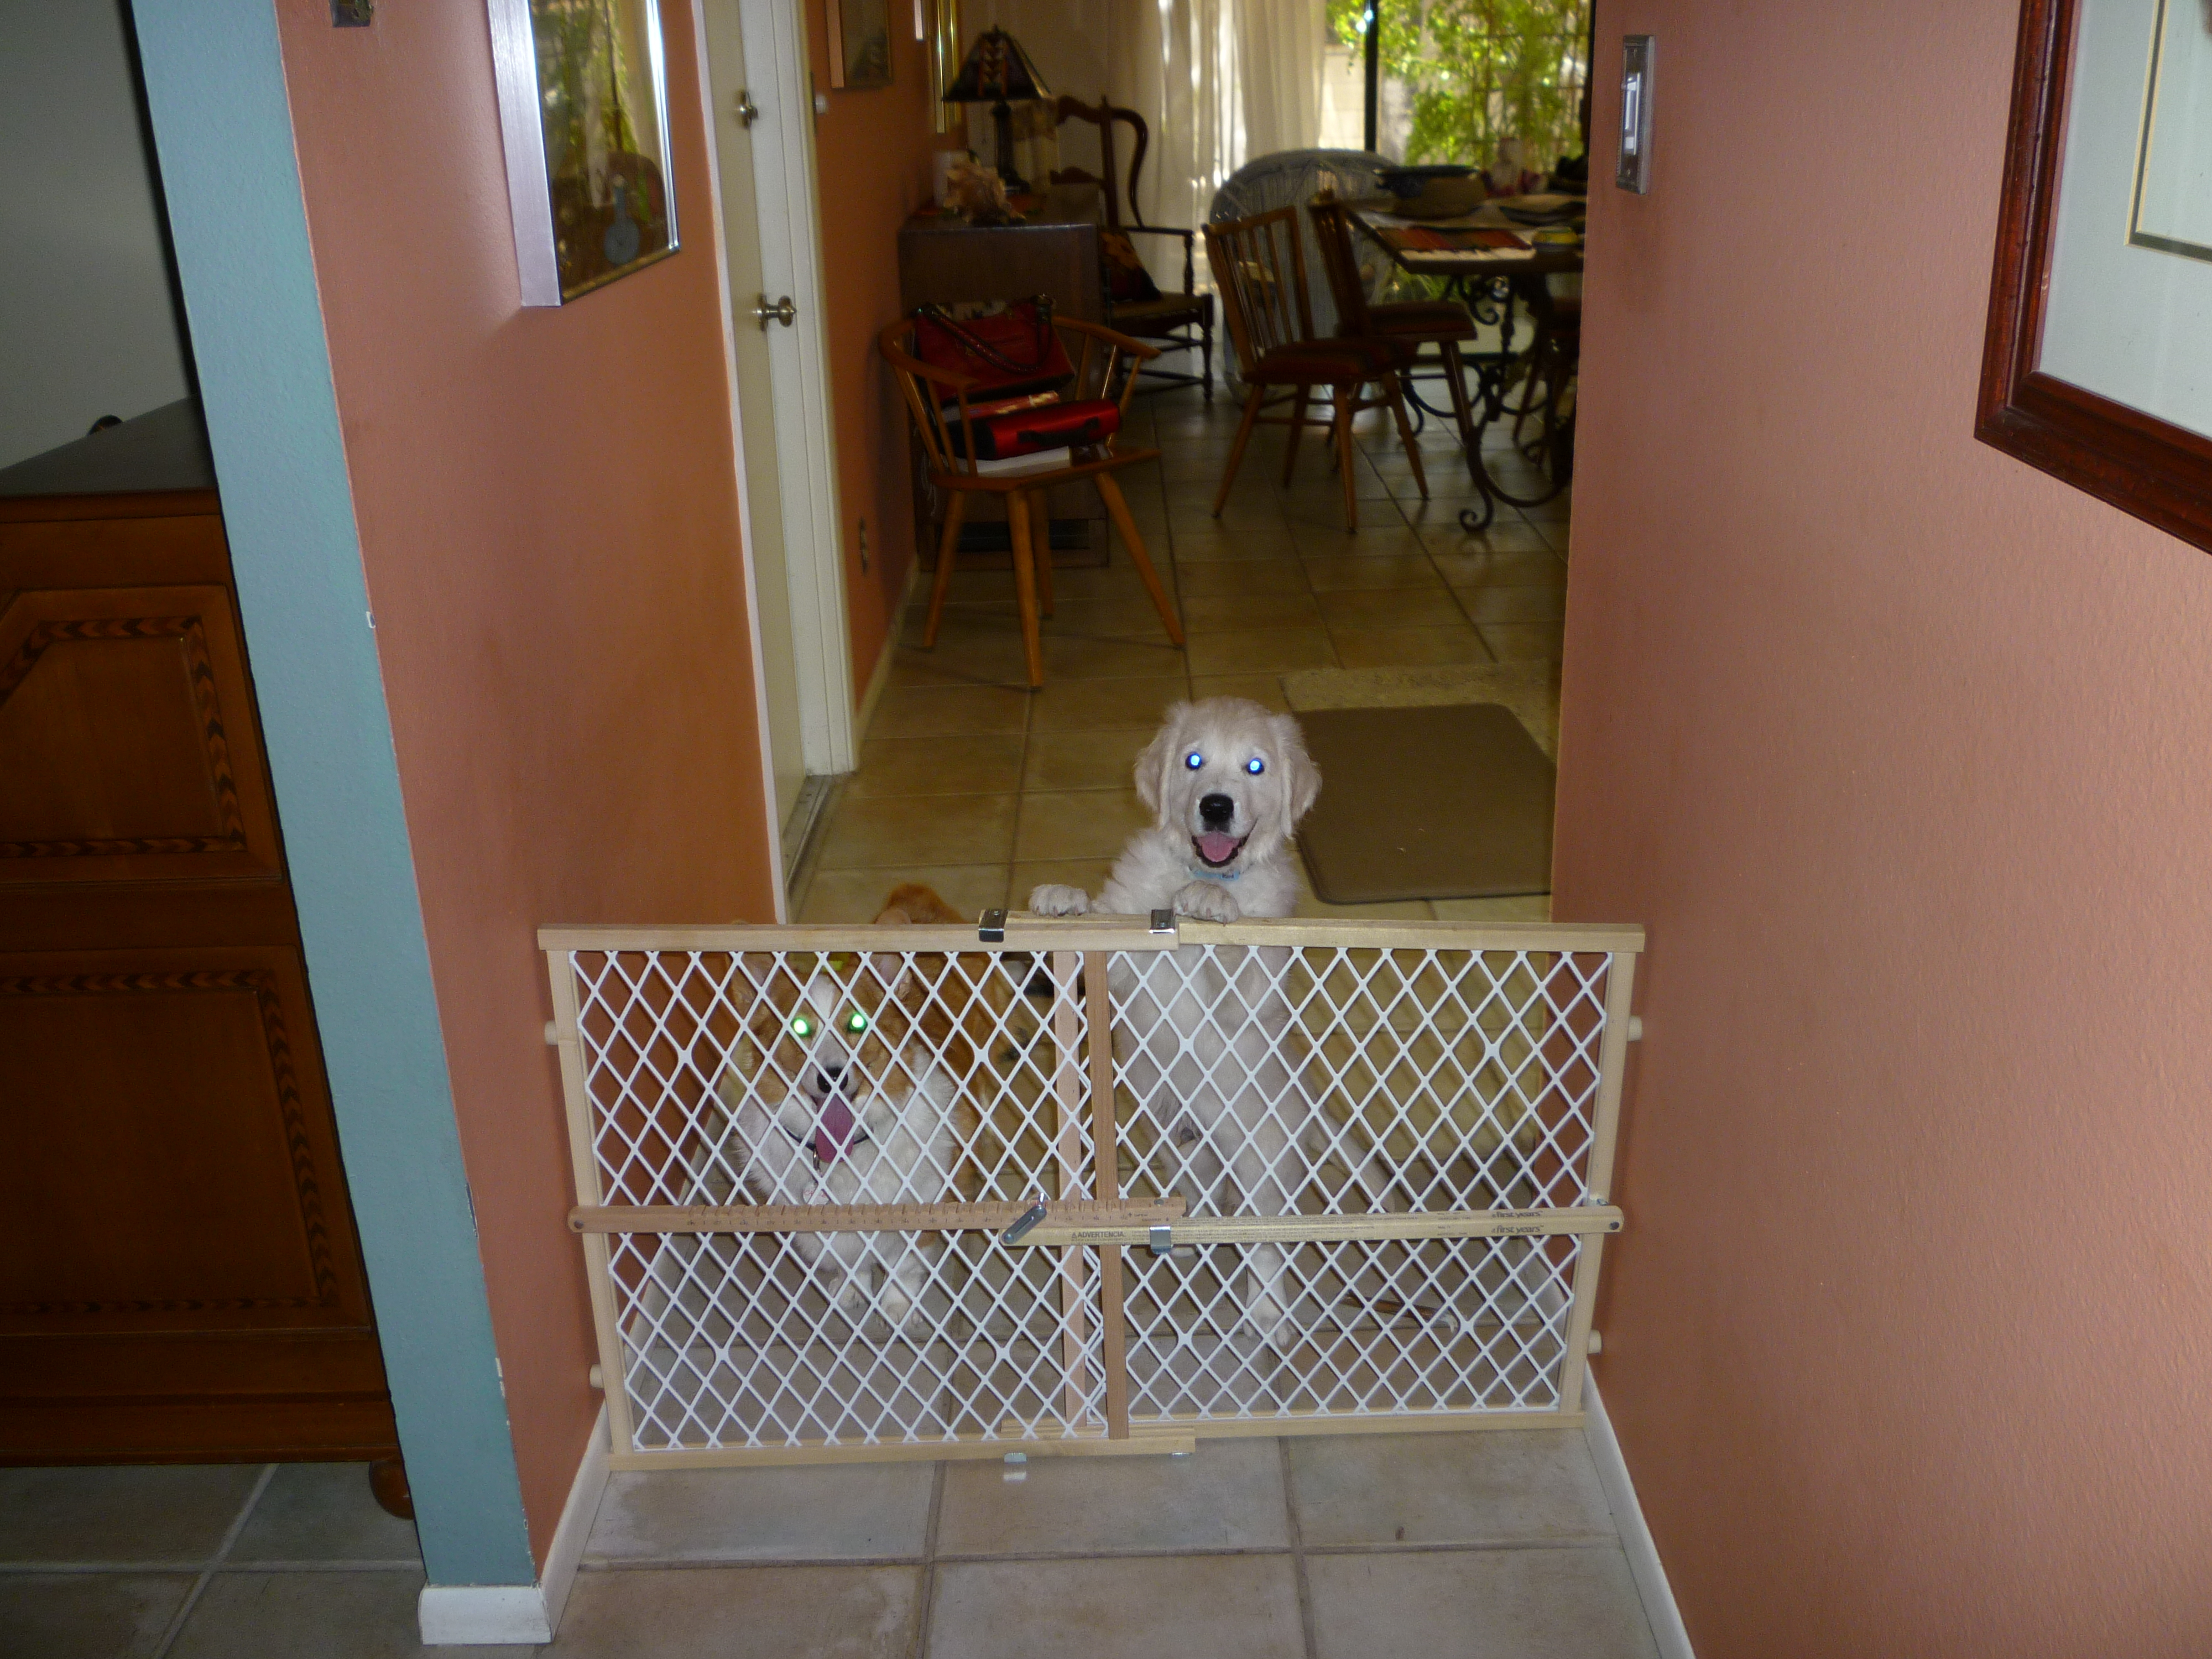
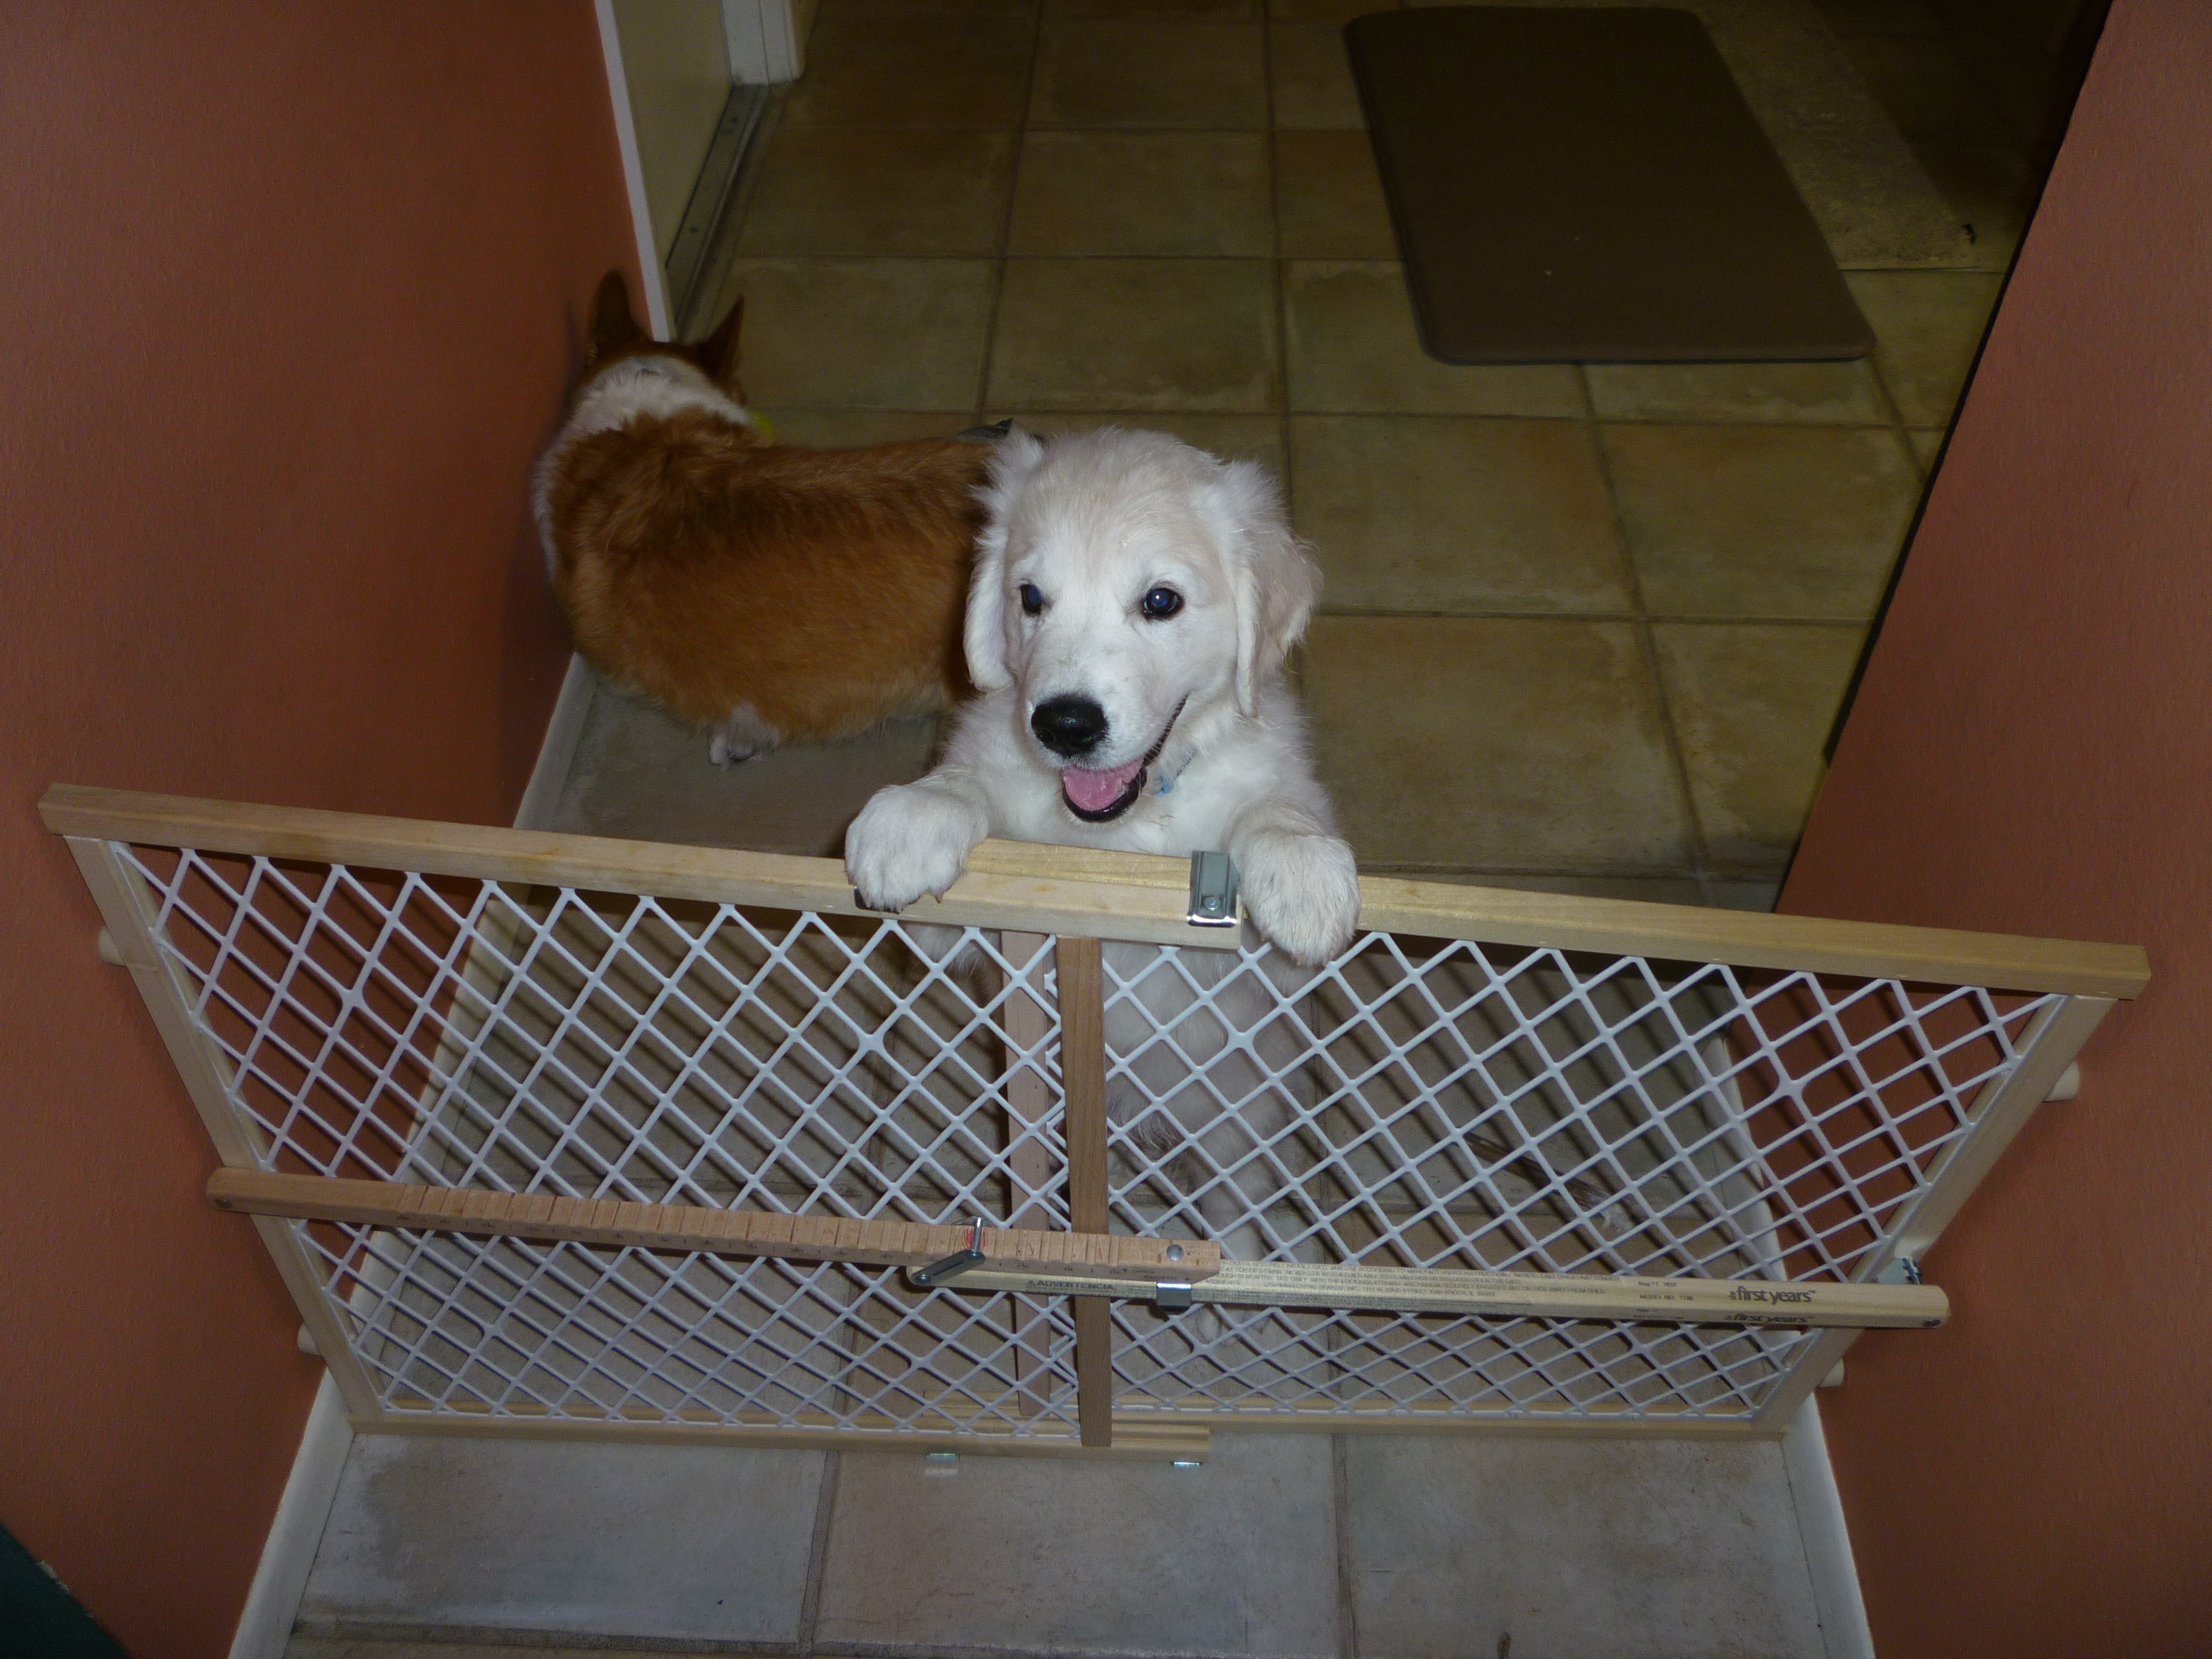
Jackdaniels is quite the active puppy. He’s been keeping me and Cassie the Corgi busy every living breathing minute between the time I get home from campus and the time M’hijito comes to pick him up, which is often quite a while, because my son regularly puts in 12-hour days.
This has been putting a crimp on my blog-scribbling and paper-grading activities. Clearly something had to be done to distract him.
Today I decided to celebrate the end of my Eng. 101 summer class with a trip to Whole Foods. Though I can’t afford Whole Paycheck, I was hungry and wanted something good to eat and there’s precious little left in the pantry. They had none of the stuff I craved: the sale on $4.50/lb wild crab doesn’t start til tomorrow and they were out of my beloved tuna and salmon poke and I can’t afford their cheeses. So it was on to the Trader Joe’s in the same strip mall, where I snabbed a very fine chunk of ripe brie and some exceptionally nice baby artichokes. And across the parking lot, what should I spot but…a fancy pet store!
Mais certainement!
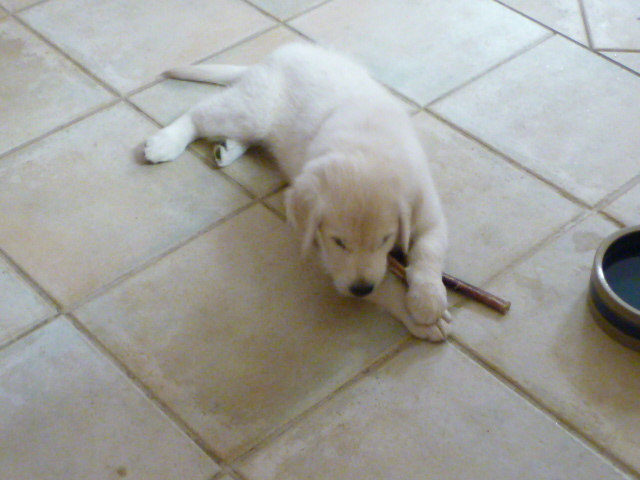
Jackdaniels has taken to chewing on the kitchen cabinetry, which will never do. So I dropped by to ask if they didn’t have some sort of chew toys that will not choke the dog, and (as I’ve read elsewhere) the salesdude said all the vets were recommending bull pizzle as relatively safe. The product is also called bully sticks. Right. For the sake of our male readers we will not discuss what these objects actually are.
Suffice it to say that the fancy pet store was the Whole Paycheck of the dog world. Bull pizzle is selling for just slightly under the price of gold, which in these panicky times is fairly high. No joke: $45 for a package of the damn stuff!
Well, I did find some six-inch pieces selling at an astonishing $4 apiece. To prevent mayhem and bloodshed, I realized I’d have to get two of them, one for the pup and one for the Queen of the Universe. And remembering how Anna the Gershep could polish off a large chew stick in about 30 seconds, I figured I’d better get two apiece: $16 for four six-inch pizzle sticks.
Hence, across the city with two bags of groceries and the gold-plated dog chews in tow.
Well, it was $16 worth of dog joy! And interestingly, neither dog has been able to destroy one yet. They must be pretty sturdy, because both pooches have been chewing happily on them for the past two hours, and neither has made much progress at consuming them.
So it looks like even though these things are stupidly overpriced, they may at least last longer than your average pig’s ear.
Cuter than cute!
Meanwhile, we’ve been dwelling in Stress City for the past few days. Oh god.
It’s effing hot here in the kitchen, where the dogs and I are penned in to ensure that jackdaniels doesn’t demolish the rest of the house. With the AC set at 80, which is about what I can afford in the summer, it’s 88 degrees here in the kitchen. And humid…sticky, sticky, icky humid. This is August. You don’t need a calendar to know that.
So this is a bit draining and does little for my enthusiasm to grade papers or clean house or work on a blog carnival or do much of anything. But…much must be dealt with.
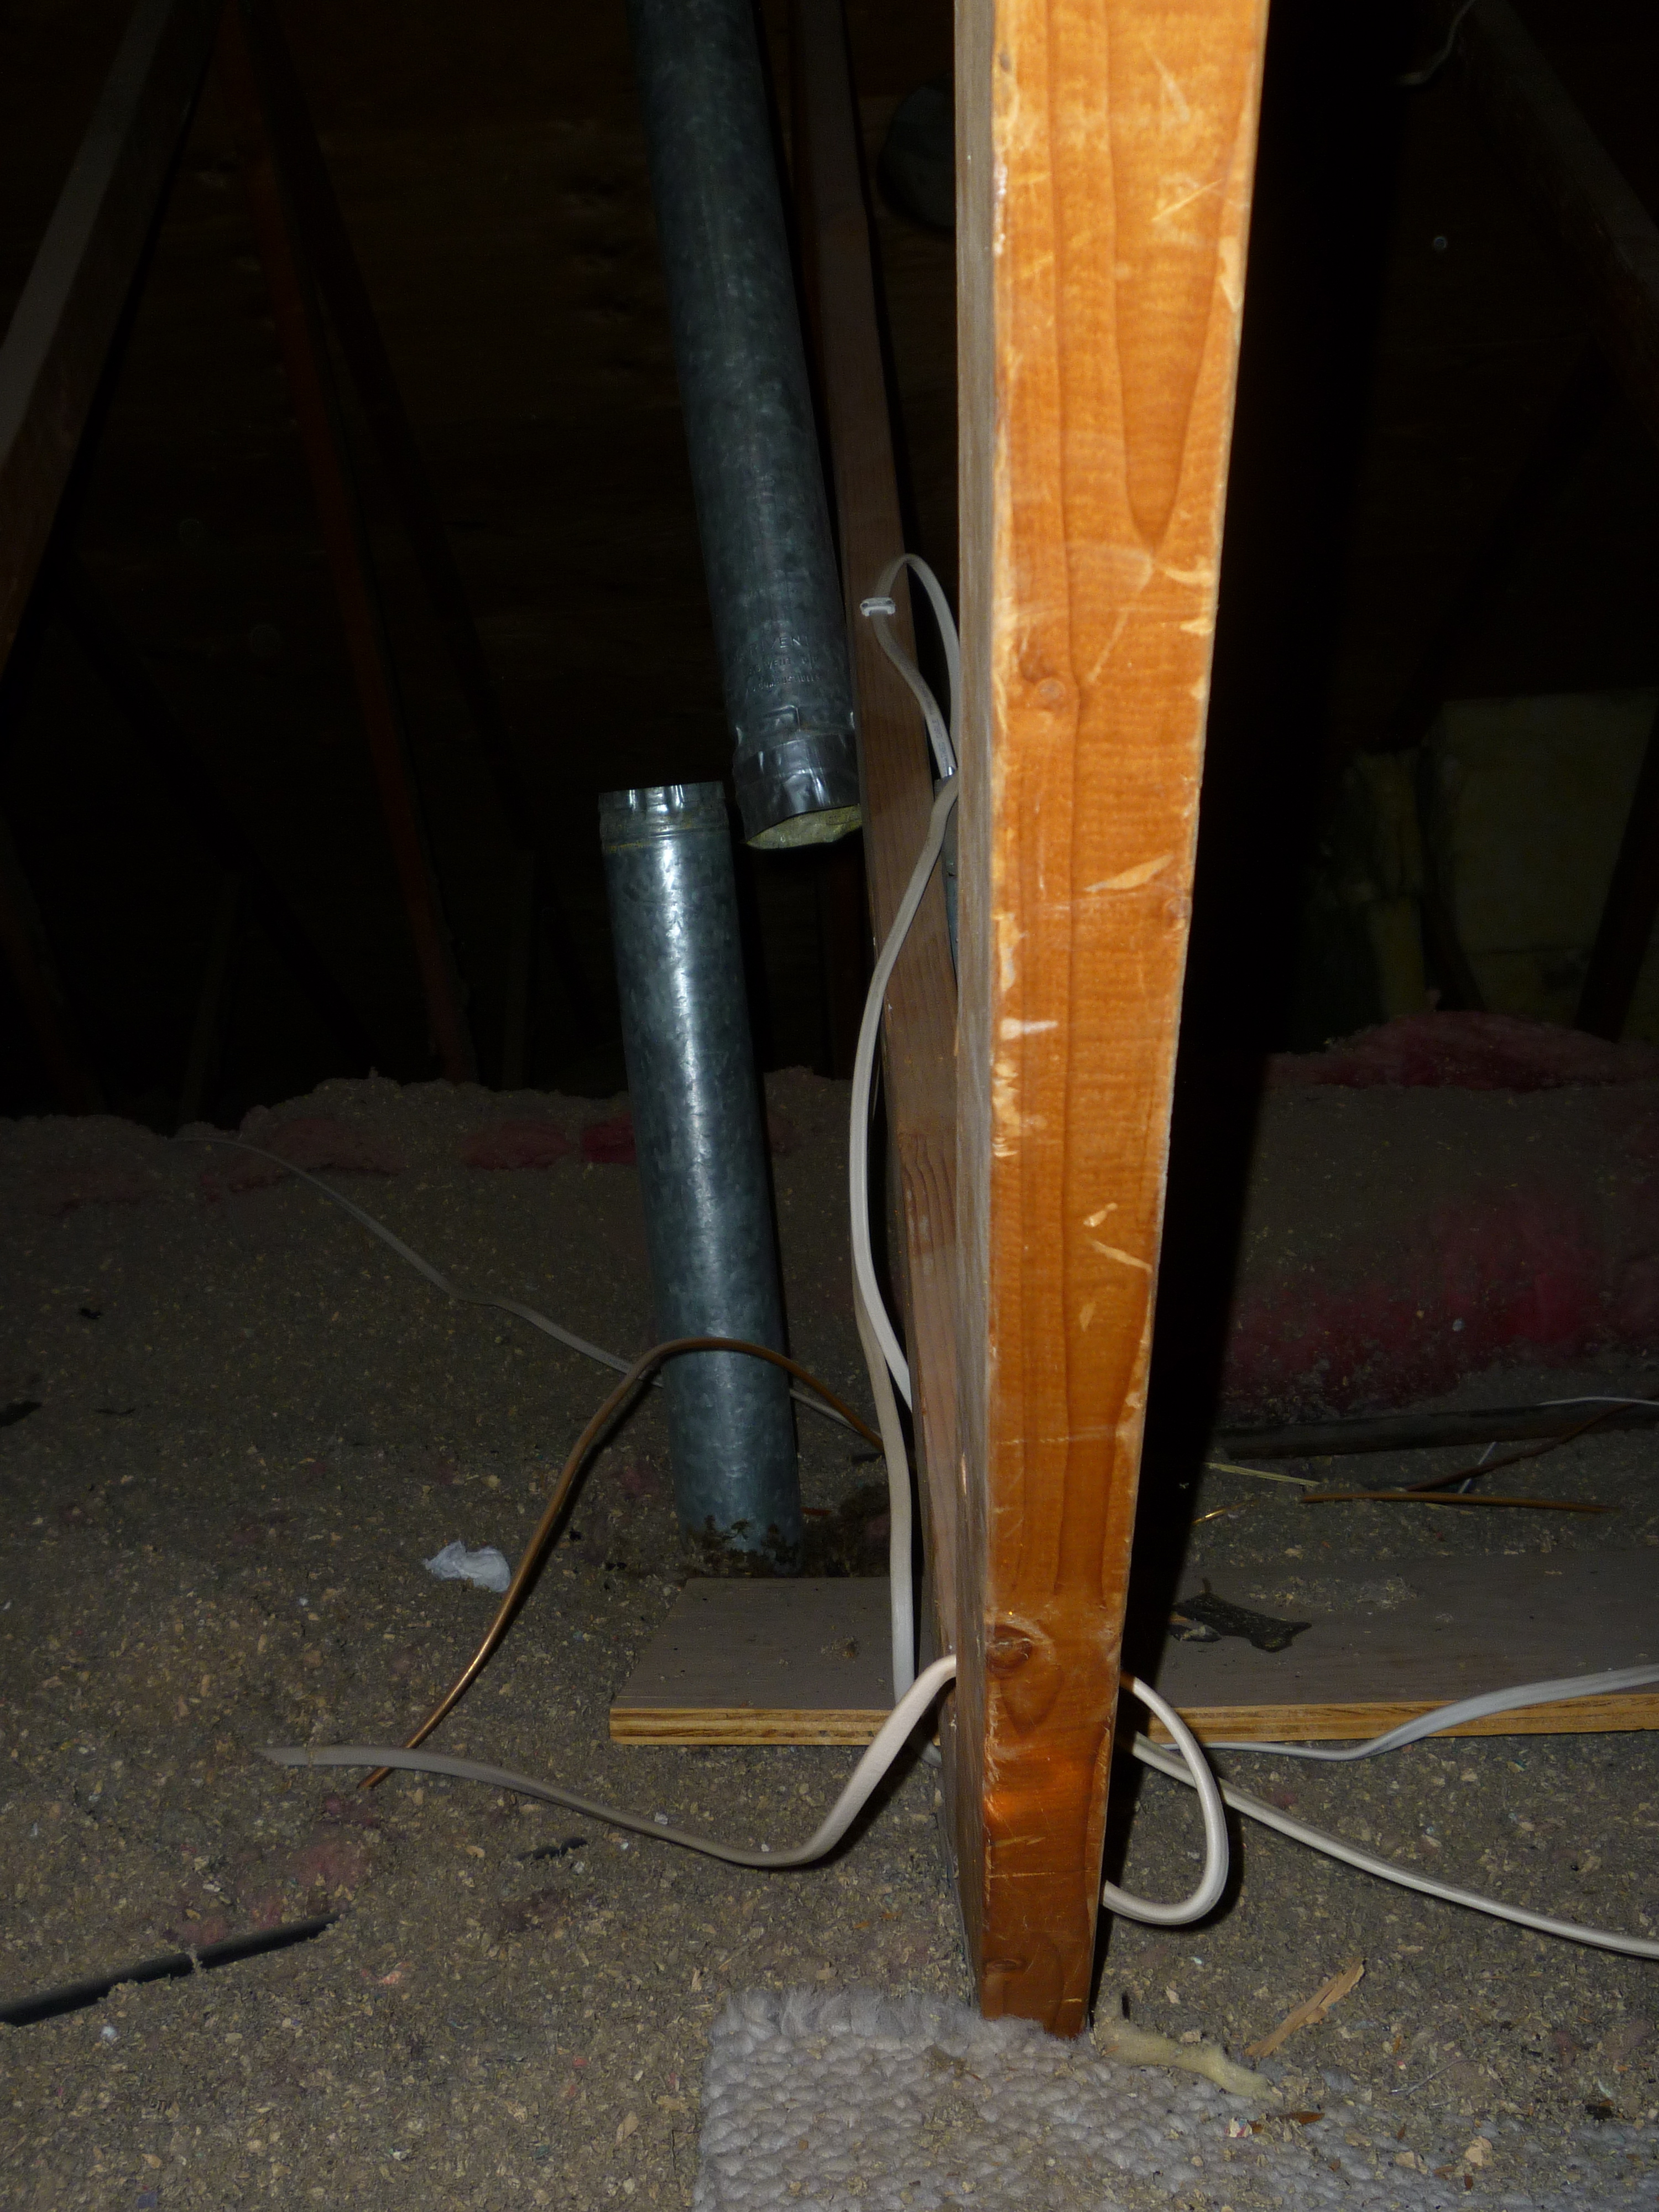
Tomorrow morning the Mr. Lutz the Trustworthy Plumber is coming over before it gets too, too hot to climb into the attic, there to examine what I expect is a half-assed repair job on the water heater vent. He said he would inspect the other vents, too, although he thinks they’re probably OK because those are hard pipes rather than aluminum ductwork. I wouldn’t put it past the roofer’s bunch, though, to have screwed those up, too.
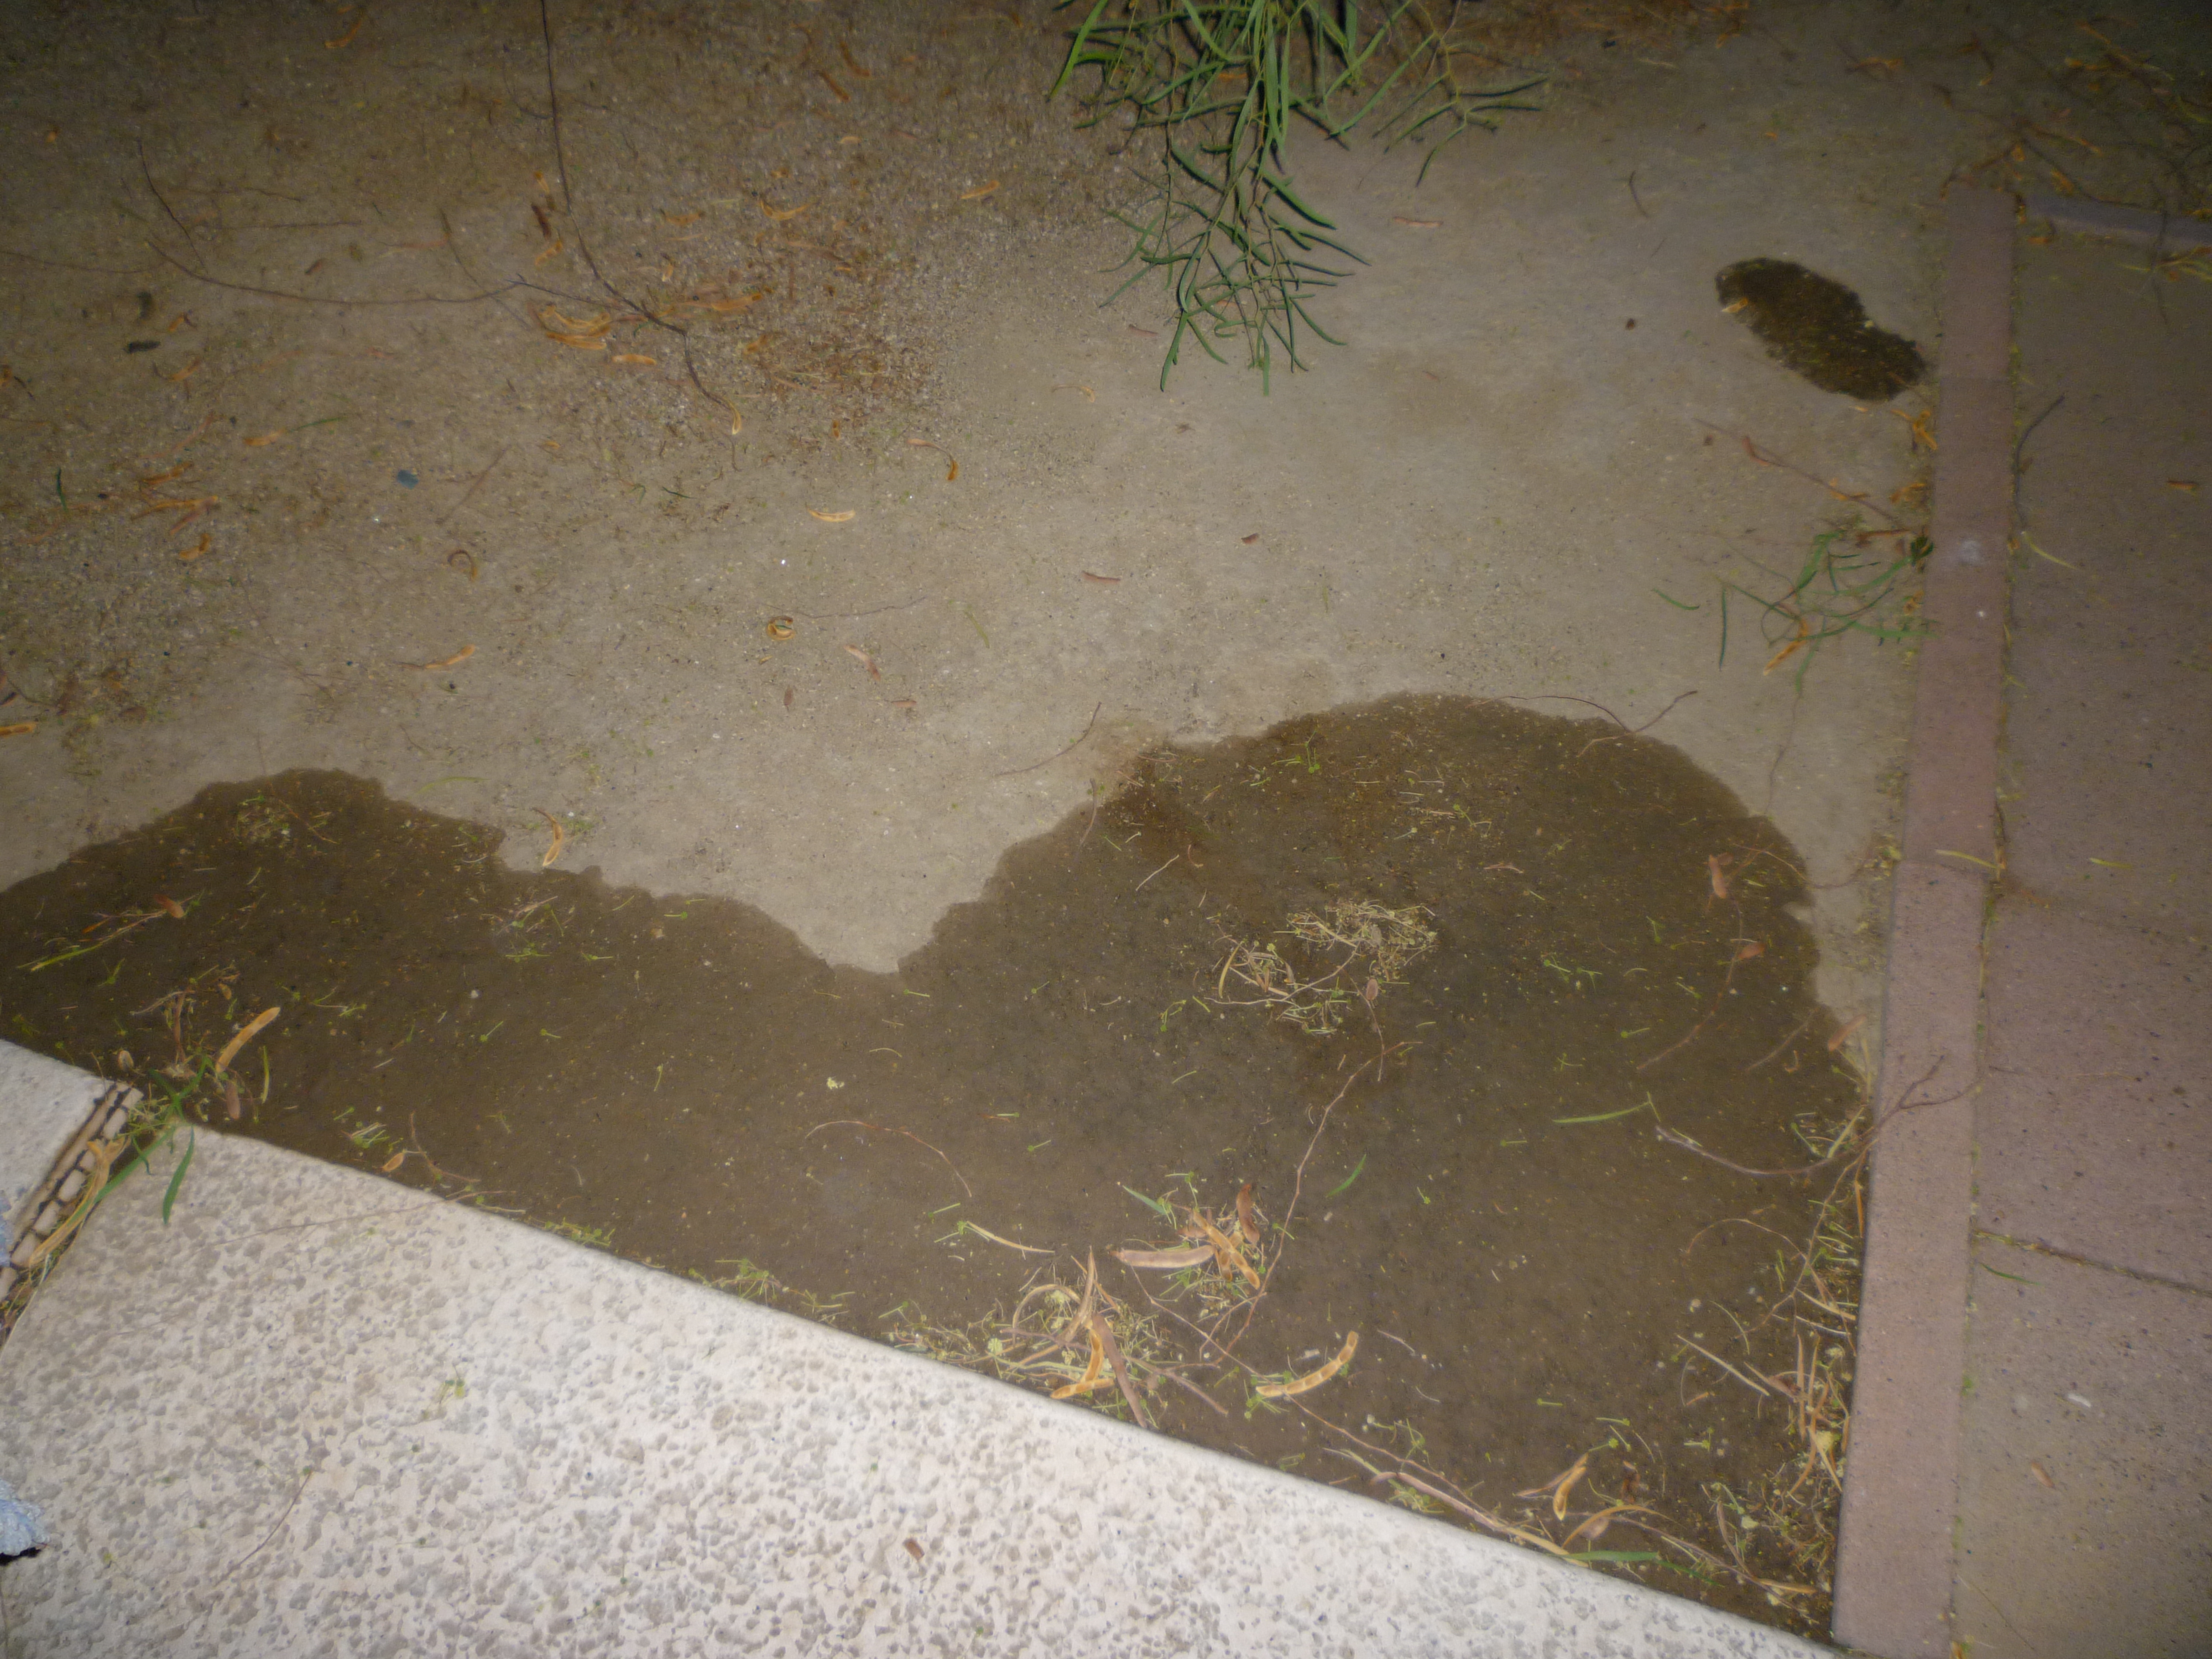
And I’ll have another little chore for him: at 5:00 this morning when I went out to shovel back the results of last night’s violent windstorm, what should I find but this nice little damp spot off the east side of the patio slab… The spot above it is dog pee, but the large puddle is neither dog pee nor rainwater. Though the north valley was inundated, we in the rain shadow of the North Mountains saw nary a drop last night.
Soooooo….one might reasonably ask, “WTF??? Where is that coming from?”
Well, there’s a hose bib on a standpipe coming off a line that runs (where else?) underneath the KoolDeck-swaddled slab that covers about 550 square feet out there. Uh uh.
Visions of jackhammers dance in my head…
One of my students is an architect, interestingly enough. I asked him what he thought fixing that would entail, and he thought that if it was actually a leak (and what other than a leak could explain yesterday’s HUNDRED AND SEVENTY-DOLLAH WATER BILL!!!!!?????), the water would not have moved in that direction.
Well, we’ll see what the miracle plumber says, assuming he can think through the sound of the cash register jingling in his head.
Damn. I’m beyond being able to cope with any more zillion-dollar emergency bills.
If I have to have the pavement jackhammered out, the plumbing dug up and repaired, the paving relaid, and the hideous KoolDeck smeared all over everything again (what is the appeal of that stuff?), it’s going to cost every penny I earn this summer plus several thousand more. Oh…damn, oh hell, oh damn!
Really. I’ve worked like an animal all summer, devoted weeks of unpaid labor to creating my own CMS in WordPress and Google Docs to get around the flicking NIGHTMARE that is Blackboard, and I’d planned to use the munificent three grand I’m earning to fold into survival savings to delay having to draw down from retirement savings another three months.
And as we see the market swooning once again, we can see that said delay is no longer a “want” but an absolute, positive need. The last time this happened, grâce à our fine political leaders, I lost two hundred grand from my savings. That loss was just about recovered, and now, thanks to the FLICKING STUPIDITY we’ve seen from what passes for our elected leadership, the money is going right back down the drain again.
And so, believe me, the last thing I want to do is pour my summer earnings into the literal drain.
Nor do I want to do what I’m about to do, which is to take off my clothes, go out in the blast-furnace midday sun, and work on the pool; then come back in and start grading student papers.
Paycheck for these past two weeks posted (but not received by my bank until tomorrow): $200 less than expected.
Bill for car repair posted on American Express: $786.58.
I don’t have that much left in emergency savings, so about $90 of it will have to come out of cash flow. But it doesn’t stop there:
Rip-off to register the car: $72.56.
Rip-off for car emission test: $27.75.
Fortunately, exclusive of the unexpected car repair bill, I came in $55 under budget this month, for the first time in recorded memory. So despite the $787 car bill and the $140 in repairs on the pool equipment and the $95 to the electrician to repair the shorted, overheating light switch, and the $140.76 in medical bills not covered by Medicare, I have yet to overdraw my checking account.
Barely. Give it time, though. Today is only the 27th. This month has 31 days. Plenty of time for some new expensive fiasco to occur.
It’s clear now that we won’t be receiving next month’s Social Security checks. Bloody lucky thing I managed to land these two summer classes; tomorrow’s paycheck is just about the amount of a Social Security payment. It will tide me over August.
September, however, is a different matter: I stashed enough in my son’s and my joint account for mortgage payments to cover the summer, but in September I have to start coming up with $717/month again. And if those bastards in Washington haven’t gotten off the dime, I won’t be able to pay it.
Okay, so just now $7,390 is left of the $28,000 of layoff savings that I entered unemployment with 18 months ago. This little stash, which I found sitting in my various bank accounts as my fine former job wound to a close, has been supporting me, along with Social Security and the irregular pittance I earn as an adjunct professor of English, while I try to delay having to draw down my IRA and brokerage accounts.
It’s lasted longer than anyone thought it would, and with any luck at all, it’s about to last another year.
The other day I revisited my ultracomplicated cash flow scheme, largely because I need to find a way to extract more monthly spending money from this Pushmi-Pullyu. The truth is, I’m not giving myself enough to live on comfortably. It was tight when I started a year and a half ago, but the increases in food and fuel costs (not inflation, right?), along with a never-ending slew of unplanned expenses, lately have made it impossible to stay on budget. I’ve been allocating $800 for discretionary expenses (a total of $2050 a month for all expenses, discretionary and fixed), when the fact is I really need something more like $1,500, for a total of around $2,750.
Unless a miracle happens (for example, I land that one-year-only job or, more likely, win the lottery), not only am I never going to earn any more than the $19,200 I’m making this year, my earned income actually is going to drop $2,400, because of the recently announced tightening of the noose around the adjuncts’ necks.
That means, I guess, the allocation from this serendipitous little “survival fund” will have to be adjusted.
Also, I’d like to simplify my bookkeeping.
What I have been doing is when money comes in, I transfer some of it to the joint account from which M’hijito and I pay the mortgage on the submerged house, transfer some of it to a self-escrow account for paying insurance and tax bills, transfer some into a short-term emergency and diddle-it-away fund, keep some of it in my checking account, and transfer $1060 from the survival fund to make up the shortfall between income and outgo. This complex shuffle no longer suffices to cover expenses. Way complicated!
So, I’ve cooked up something slightly different. In some ways, it’s six of one, half-a-dozen of the other (or, could we say, robbing Peter to pay Paul?). But it’ll give me a little bit more money—raising the discretionary budget to about $1,100 most (but not all) months—and the process will be simpler. I can’t afford the amount I actually need, but even a little increase will help.
Instead of moving money from Survival Savings to checking in amounts that supplement Social Security and teaching pay, I’m going to go the other way around: move every penny of income—Social Security, teaching, bank heists, windfalls—from checking to Survival Savings. Then, once a month, I’ll pay myself $2,300. If any cash is left from the previous month’s budget, I’ll just “top up” the checking account to reach a base figure of $2,300.
This gives me a raise of about $250 a month, which I hope will cover the increase in routine expenses.
The problem with figuring out whether this will work and what it will do to the Survival Fund’s longevity is the extreme irregularity and unpredictability of adjunct income. From pay period to pay period, I rarely know what my check is going to hold. One week I can get $300, and two weeks later it’ll be $800 or $1,000, with no clear rhyme nor reason. HR seems not to know how to figure out what one will be paid, and not being an accountant, I can’t even make an educated guess. All I know is that during the summer when I most need extra money, my teaching pay drops into the basement, and during the month between fall and spring semesters I get nothing.
The only way to project the effectiveness of this scheme—and the length of time the Survival Fund will last—is to enter 2010-11 pay amounts into a spreadsheet showing how the new transfer scheme will work.
The upshot is surprisingly positive. Well…all things considered. Transfers into and out of Survival Savings look like this:
If my amazingly tedious calculations are correct, Survival Savings will run out in August 2012. At that time, I’ll have to cash in a whole life policy; the post-tax balance from that will probably stretch another year or 18 months. After that…well, let’s hope the stock market is doing OK, because at that point I’ll have to start drawing down investments.
During the winter break and the month or so of summer that I’ll have no income, I’ll have to drop my living-expenses budget back to its present level, $2,090. This will be difficult next summer, because utilities are so high during the heat and because, as we’ve observed for the second summer running, everything goes wrong when you can least afford it. However…that comes under the heading of tough nougies.
If all this comes to pass as estimated (a very big If, indeed), then I should be able to live adequately and pay my share of the mortgage without exhausting Survival Savings until a year from this August. Might even be able to stretch it out for another month or two, if I can keep expenses significantly under $2,300 for several of the cooler months. That’s not unreasonable; when nondiscretionary bills are at their lowest, I can have a surplus of $300 or $400. Four of those would keep that $7,390 grubstake going through September.
Obviously, I’m not thrilled at the precariousness of this system. On the other hand… I feel like it’s really not too bad. If in fact the insurance payout will last another 18 months or so, then I will have succeeded in pushing back the time I’ll have to draw down investments for four years after Canning Day.
Those investments have about recovered their former, pre-Crash glory. Assuming our esteemed leaders don’t bring on another market crash with their grandstanding shenanigans, a 4 or 5 percent drawdown plus Social Security (assuming, again, that it still exists in 2013 or so) should cover my expenses and pay the mortgage—without benefit of flakey part-time teaching income.