Coffee heat rising

Ridiculous Retirement System: With a Vengeance

Various of our PF blogging friends have noted the dangerously low savings rates among middle- and working-class Americans, mostly by way of urging readers to set aside larger amounts in their 401(k) and other retirement accounts. Get Rich Slowly has suggested that a million dollars is not enough to support you in your retirement (in 20 years it’ll be worth all of $449,400 in today’s dollars) and that you should be investing between 4.2 and 5.7 percent of your income, depending on your age.

That is extremely low. I put 7% of my pay, matched by the Great Desert University for a total of 14%, into deferred savings, and I started that job with $250,000 in an IRA and another $80,000 in nondeferred brokerage accounts. I started that job 20 years ago. Today, laid off my job and essentially unemployable at age 67, I have just over half a million bucks. And that is nowhere near enough to live on through one’s dotage.

Economics professor Teresa Ghilarducci points out the fundamental problem: expecting everyone to set aside enough in self-directed, commercially operated savings funds to fund 20 or 30 years of unemployment (which is what “retirement” really is) has proven to be a massive failure. So much so that she brands it “ridiculous.” Our present 401(k)/403(b) retirement system, she observes, “simply defies human behavior. Basing a system on people’s voluntarily saving for 40 years and evaluating the relevant information for sound investment choices is like asking the family pet to dance on two legs…. This do-it-yourself pension system has failed. It has failed because it expects individuals without investment expertise to reap the same results as professional investors and money managers. What results would you expect if you were asked to pull your own teeth or do your own electrical wiring?”

The chickens, my friends, are flying home to roost as we speak. Most older workers cannot hold their jobs until they’re 70 (or older). The cold fact is, people over 50 have faster-growing rates of unemployment than any other group. And once you’re over about 45 in our youth-obsessed culture, you are going to have a very difficult time getting another job. If you’re 60 and older, forget it. The likelihood that you’ll land another job is almost nil, and if you do, it will be at an enormous cut in pay.

As Ghilarducci points out, “Almost half of middle-class workers, 49 percent, will be poor or near poor in retirement, living on a food budget of about $5 a day.”

Over at Wealth Pilgrim, Neal Frankl explains, with crystal clarity, why you will need about 20 times your present earnings to maintain your present lifestyle. It means that if you have an income of $50,000 today, your nest egg will have to amount to $1 million to support a middle-class lifestyle through the likely end of your life. That, my friends, is with a 5% average return on investment, which you may or may not achieve. “May not” is probably the operative term for funds managed by the do-it-yourselfer.

Using Neal’s rule of thumb—which adds up to the same ratio Ghilarducci cites, 20 times your present income(!)—to have a reasonable chance of maintaining a rather ordinary lifestyle through my dotage, I would have needed $1.2 million in investments when I was laid off at the virtually unemployable age of 64. That’s more than twice what I actually do have.

Neal’s calculation is a little more forgiving, because he asks you to figure what you will need to draw down from investments, which allows you to take into account details like Social Security, the amount of your revolving debt, whether your home is paid off, and whether you live in a high- or low-cost-of-living state. Simply divide the amount you will need by 5%, the projected rate of return on investments.

In my case, I need a bare minimum of $25,000 (a figure that grows with every tax increase, every utility increase, every auto and homeowner’s insurance increase, and every jump in food and gasoline prices). In theory, then, my half-million-dollar nest egg will support me. Just barely. Assuming Social Security continues for the rest of my life, something that is decidedly not a given.

The truth is, I really need more like $30,000 to $40,000 from investments, since that $25,000 allows for a lifestyle that we might call “pinched.” If I want to go out to eat more than once a month, might like to travel a bit, wish to wear clothes that don’t come from thrift stores, then I would need $600,000 to $800,000 in savings. And those savings would need to be intelligently invested.

Understand, $40,000 plus Social Security comes nowhere near what I was earning when my job came to an end. So under the best retirement scenario, which is impossible because I have nothing like enough to establish that scenario, I’m looking at a significantly diminished lifestyle. One, we might add, that will continue to shrink over time.

As Ghilarducci points out, a retirement “system” that is going to leave 75 percent of Americans in poverty when they hit old age is ridiculous: “failure is baked into the voluntary, self-directed, commercially run retirement plans system.” She suggests mandated, guaranteed retirement accounts, to be professionally managed and to pay out in annuities, on top of Social Security.

It’s a little late for those of us who have already been involuntarily retired or who are still working but don’t have a chance of setting aside 30% or more of gross income. But for the younger generations: something needs to be done, and soon. The coming “retirement crisis” is going to affect everyone. As I’ve pointed out myself, when Baby Boomers sink into poverty, their adult sons and daughters will be called upon to support them.

What we have here is a retirement system that’s ridiculous not only for the vast number of workers who are edging toward old age, but for everyone else, too.
 

{sigh}

What a depressing week. Yet another madman goes off the deep end; the President of the United States calls for “justice” and all the anti-gun nuts rattle their tambourines again, but not a soul remarks that we need a medical system that includes mental health care and that has the capacity to hospitalize and treat dangerous lunatics. Elsewhere, the Syrians stay busy killing each other, the Arab extremists have reached out to Bulgaria to kill Jewish tourists (or so we’re told…), and a U.S. ambassador opines that Israel has the right to defend itself, presumably countenancing more retaliation. Meanwhile, at least one of the girls who disappeared last week in Iowa is the child of a meth dealer. Lovely.

On the local level, I bombed the interview to get my little enterprise into the two year AAAME program yesterday. Failed to make them understand what we do and why it should matter and ended up with one of them remarking that my business is not a business but a hobby. Right. I get up at 4:30 in the morning six or seven days a week and work all the way through to 10 o’clock at night for a “hobby.”

Oh well. I guess we’ll just have to figure out how to make the thing work on our own.

As a practical matter, we’ve been doing pretty well over the past couple of months. Our biggest challenge now is marketing—getting desirable work to come in steadily—and clearly in that department the issue is to make other businesses understand how much time we can save them, and how having professionals prepare their major documents improves over giving the job to some admin or to a committee of employees who are already fully occupied with the the tasks that fit their own job descriptions.

So…is anything less depressing going on in the world? Surely there must be something…

Donna Freedman is seeking votes for not one but two of her excellent articles in the Financial Olympics. She explains how to cast your vote. If you like Donna’s writing as much as I do, you should follow the links in at her post and vote for her.

A while back, Neale Frankle posted a nice piece titled “Why You Are Broke: Top Ten Reasons.” Some of these are pretty insightful: among them, marrying the wrong person and divorcing. To which I say yup, divorce’ll do it to you! If I had stayed put, I’d still be living with a man whose remarks about me behind my back were so mean-minded one of his acquaintances told me he would have no more to do with the man. But I wouldn’t be trying to get by on $25,000 a year (at best), either: by now he’s making almost three hundred grand.

There’s a very interesting discussion at Invest It Wisely: three articles positing that you could live to 100 and therefore should have an investment portfolio to keep you going that long. The last of these contains links to the first two. It’s an intelligent—and, one might add, unusually conservative—approach to retirement saving and drawdowns.

Nicole&Maggie, nearing Due Day, report that it’s mighty nice to have money to throw at a problem…and how they got to that point.

Teacher Man reflects, with dark humor, on the profitability (for him) of other people’s stupidity when it comes to credit cards.

Over at Brip-Blap, Steve contemplates the things that interfere with creativity.

Eemusings posted photos of the Sydney trip this week. Gosh!

TB has an encounter with one of the Dumb and the Feckless who populate our planet. {sigh} Where do they all come from?…

Good news at Budgeting in the Fun Stuff: Mr. & Mrs. BFS can now actually SEE the outline of their new house! Quite the palace, eh?

Evan explains what is meant by “invoice factoring” and how an entrepreneur can use it to raise cash without going into debt.

Which brings us back to one of the topics I began with and reminds me I am wayyy too depressed to keep writing this morning. And so, to breakfast…

Why I Hate Teaching

It’s not just because it’s stupidly underpaid.

Not because you have to establish a Roman emperor’s dominion over teenagers who are disrespectful to everyone around them.

Not so much because the benighted ignorance with which American students pass out of secondary schools leaves one weeping for one’s country and for its hapless children.

Not because reading their drivel is excruciatingly time-consuming and excruciatingly boring.

Not even because spending one’s time trying to assess said drivel intelligently and trying to advise its authors in ways to write less idiotic pap is a heartbreaking waste of energy and hours.

No. Not necessarily those things.

It is because no matter how much effort you put into them, no matter how much faith and hope you invest in your students, sooner or later they will disappoint you.

And you will be disappointed not just in them but in yourself and in your profession and in the entire flicking society around you.

They cheat. They lie and they cheat. And they do it all the time. It is so routine as to be unremarkable. And it’s not the ones who are so hopelessly dense that they have to cheat to pass a lightweight course like freshman comp. No. Half the time, God help us, it’s the smart ones.

I just returned (and forwarded to the division chair) a 300-point paper that failed because a good third of it is a copy-and-paste job.

Annoyingly, the author is one of my favorite students. She’s bright and gregarious and funny and she even seems to be paying attention in class. And, even more annoyingly, she’s no young kid who might be expected not to know better. This is a grown woman, thirty-five…maybe even pushing forty. And she’s a pretty typical plagiarist: smart, articulate, and full of potential.

Why do they do this? They’re not cheating anybody but themselves. They’re not cheating me. They’re not even cheating their classmates, since every person who enrolls in a college course gains from it as much as she or he individually puts into it. Why would you pay for something and then waste your time and energy on it? Is it arrogance—are they so smart they think they don’t need to be bothered?

When I was a kid, I was too terrorized to do this kind of thing. I would get caught (for sure!), and then I would be thrown out of school. My mother would weep and my father would disown me. I would spend the rest of my life in abject disgrace. So socialized was I to believe that you could not get away with cheating, lying, stealing, embezzling, arson, or murder that it wasn’t until I reached my mid-40s that I began to realize how much people do get away with. It was about then that I met a young woman who had spent a fair amount of her adult life committing insurance fraud.

She was minting money and new cars. Even whole new houses—twice she got insurance companies to tear out and rebuild the interiors of entire dwellings! That was an eye-opener.

By then I was on a university faculty. Informed by my young friend’s revelations, I began to notice the number of colleagues who pretended to serve on committees. They’d show up (sometimes) at meetings, do exactly nothing, and at the end of the day take credit for the work two or three other people on the committee actually did.

Should I mention the associate dean who arrived at his elevated position (and salary) on the strength of a three-volume magnum opus? When you opened the covers, as apparently few of his colleagues ever did, you discovered it consisted of offprints from the Congressional Record! Yes. In three volumes, the only parts he’d written were a short introduction and a series of two- or three-paragraph headnotes: maybe 35 or 40 pages in total.

How about the associate professor who was asked, three years running, to write a proposal to establish a program for which funding and administrative intent already existed and who never could manage to choke out anything acceptable, and how the program didn’t happen until a certain non-tenure-track lecturer of your acquaintance sat down and wrote the damn thing?

The search committee that was determined to hire a minority to its faculty, even though they openly admitted that a WASP woman was by far the best of the applicants? When the single African-American applicant accepted a job elsewhere, they closed the search rather than hire a better-qualified white candidate, and they conspired to flamboozle the Affirmative Action office with a set of phony reasons for rejecting her.

Dishonesty and cheating and devil-take-the-hindmost ethics are endemic to our culture, from the kid who pastes a web page into a term paper to the merchant who sells second-rate goods at first-rate prices to the manufacturer who fills “NEW!” packaging with less product at the same price to the pharmaceutical industries that foist unnecessary and even harmful drugs on “patients” who shouldn’t even be patients to bankers who entrap borrowers in loans everyone knows they can’t repay to crusading politicians who think the end justifies the means to presidents who lie to get us into unjust wars.

No. It’s not because they’re arrogant that the cleverest students cheat. It’s because they’re smarter than I was at their age. They’ve already learned they can get away with it, because everyone gets away with it. It’s the thing to do.

That is why I hate teaching. It is, in a word, profoundly demoralizing.

T-Mobile Drags Dinosaur into the 21st Century

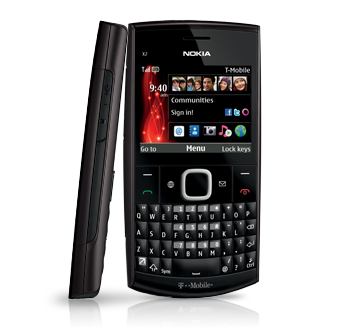
ApatosaurusWell, that was an adventure. The new Nokia phone finally arrived from T-Mobile. Of course, I knew very well that there’d be no way I could get the thing hooked up to the ambient microwaves, but I didn’t anticipate that I couldn’t even figure out how to open it to insert the sim card. So right off the bat, it was off to the T-Mobile store, which resides in a run-down Albertson’s shopping center just down the way.

They managed to get it open (turns out you need thumbnails…both mine broke off at the quick earlier this week) and set up the sim card and reinsert the battery. Brought it home and charged it up while I went on about my business, which this week has been considerable.

Next, I couldn’t get it to turn on. Kept pressing the “on/power” button to no avail.

Back to the store. Turns out you have to hold the power button down until the phone responds. Hm. How hard would it have been, dear Nokia, to have said so in your instruction booklet?

Now I go to the website to enroll in the plan of my dreams, which is not available through T-Mobile’s stores. It is so not available that live human staffers don’t even know it exists. None too available to customers, either: when I click on the link, nothing happens.

Back to the store. This time I schlepped my laptop, figuring I could attach to their wireless and, if they could just show me how, sign up from there. Well, of course their wireless wouldn’t allow me on, and they are not allowed to sign people up in the store for Internet offers. They try. Doesn’t work.

So, incredibly—hang on to your hats, Consumerism Skeptics!—one of the guys there actually offers to walk over to the next-door Starbucks, where I can get my laptop online, and get me signed up!

Can you believe that?

That is not only consumer service, it’s Consumer Service Above and Beyond the Call of Duty. I was amazed.

Didn’t take very long to get online, with someone who knew what he was doing  at hand. So I was able to send a brief text-message to M’hijito, which, as expected, spooked him. Reply: “Is this my mother?”

Well, I hope the service level remains that extraordinary. It’s a refreshing change from 21st-century business as usual!

Credit Cards: Will a Use Surcharge Change Your Habits?

Last week’s zillion-dollar settlement with Visa and Mastercard, in which merchants at last will be allowed to charge cash customers less than those who pay with credit cards (a transaction that can cost the merchant upwards of 2 percent on every sale), may mean some serious changes for consumers. In their contracts, credit-card issuers impose restrictions on merchants prohibiting the practice of charging more to people who run up the cost of business by charging purchases. As a result, we all pay more, because the only way a retailer or service provider can recover that expense is to increase prices for everyone.

Wouldn’t it be nice if those of us who prefer the convenience of credit and debit cards paid for the privilege, and the rest of us paid the actual price of goods and services?

That may come to pass.

Already, according to a report in today’s Times, ScanMyPhotos.com has lowered prices by 2 percent, and Kroger supermarkets may institute a two-tiered pricing scheme: less if you pay with cash, more if you pay with a card.

If you’re a regular reader here, you know I pay for everything with credit cards, preferably with American Express, and then settle the bill in full at the end of each month. Two reasons for this:

• a guaranteed paper trail, and
• generous cash kickbacks from AMEX and MasterCard.

Three reasons, actually: cash flows through my fingers like water. I can spend two hundred dollars in a day and have no idea where it went. The extra trouble entailed in signing for a credit transaction—plus knowing that in a few weeks I’ll have to come up with a big chunk of cash to pay the month’s accrued bills—makes me think twice about buying something I don’t really need.

I used to pay for everything with checks. There, too, the hassle factor entailed in dragging out a checkbook, annoying other customers who had to stand around while I wrote a check, and a complicated bank statement to reconcile tended to work against impulse buying and casual overspending.

If merchants start charging less to cash customers, will you abandon your credit cards? Or is the card’s convenience something you’re willing to pay for?

Pour moi, I certainly will start paying by check again. In my case, though, I don’t travel much. If you’re on the road a lot, you’ll still need a card to make airline and hotel reservations. But there’s nothing to stop a person from keeping just one card and using it only for travel costs. I love my credit cards, but I’ll be darned if I’m going to pay 2 percent more for groceries and gasoline.

Et vous?

Rainy Day and Reading

Once again, here we are in the dead of July and it’s cool enough to shut off the A.C.! A miracle! Well…a fairly steamy miracle for most of the day. A fairly flamboyant rain storm passed to the south of us—probably dropped a fair amount of rain and hail on Mr. and Mrs. Accountability, who live off in that direction. All day long the rain was trying to work itself up into a storm, despite 90-degree temperatures. By midafternoon the air was so wet it felt like it was going to start raining inside the house!

Each day I’ve been trying to to an hour or so of physical work in the yard. One has to get started very, very early to pull that off without expiring of heat stroke, so it was up at 5:30 to start pruning the Texas sage whose limbs have grown down into the pool.

It’s been slowly going off the deep end (heh! literally), but I’ve let it grow because it’s kind of pretty, with its blossom-laden branches curving into the water. But as a practical matter, it’s not good for the pool water. So it was past time to trim it up.

And that was quite a job. The problem was, I couldn’t reach all its branches from the deck. To get the whole job done, I had to get into the pool with the big nippers in hand and cut limbs from beneath…a trick when your feet don’t reach the bottom and you can’t get any purchase.

Cut out a wheelbarrow full of feral growth. I was worried that it would wreck the plant, but as it developed, the Texas sage has a pretty branch structure that was now visible once all the overgrowth and deadwood were gone. It actually turned out looking pretty good.

Later in the day, I came across this interesting post at Forbes, suggesting that one can assess (practically at a glance) whether a  new business enterprise will succeed. So far we’re scoring four out of five, and the fifth sign of success is one we’re definitely working on.

Speaking of success, over at Budgeting in the Fun Stuff, Crystal has published her first e-book, one with a tantalizing title: How I Make Money Blogging. Buy it here, and maybe you, too, can quit your day job! 😉

Abstract Aucklander’s eemusings is back from Sydney and working so hard she hasn’t had enough time to take a deep breath.

Evan ruminates on getting started early on building a retirement income stream. Now all we need to do is get all the other 20- and 30-somethings in America to plug into that idea!

Speaking of working your tuchus off, TB has been in the thick of the storm cleanup, hauling trees and dodging electric lines in 100-degree heat. I expect we’ll be seeing guys doing the same here tomorrow: a freeway flooded, cars were washed off roads, and a gigantic mess was had by all.

Money Beagle’s toddler has developed a passion to strike fear into a frugal parent’s heart!

Have you noticed that more and more young people seem to be suffering from shingles? A vaccine exists—it’s not guaranteed to prevent the excruciating resurgence of childhood chickenpox, but they say it does at least make for a milder case and faster recovery. Poor Girl Eats Well describes the effects of this ailment in vivid detail, and then she points out that the FDA has approved the shot only for people over 55. That’s something that needs to change.

On that note, it’s time to move along.