Coffee heat rising

Pay Off a Mortgage or Invest the Money Instead?

Yesterday at the weekly Scottsdale Business Association meeting, the assertion was again made that you should never pay off a mortgage in advance. If you have the money to do so, we’re told, you’ll come out ahead if you invest the money in securities and keep making those mortgage payments.

I wonder about that.
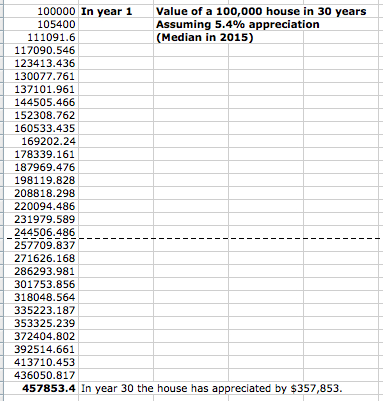
housevaluespeculation2Years ago, I paid off my $100,000 mortgage. (Can you believe I managed to wiggle into a North Central house for a hundred grand? Another recession was on: it was during the savings and loan fiasco.) The university had hired me into a full-time position, which though nontenurable, paid as much as an assistant professor in my department earned. SDXB was paying half the mortgage, which I carried on my books as rent, turning  the many upgrades the house needed into tax deductions.

With a year or two of alimony to go, it occurred to me that a) I would like SDXB to move out of my house and b) if I were covering the monthly mortgage payment myself, it would consume exactly half my net pay. Even with SDXB’s help, I was spending a little more than my entire net pay each month; if he left, I wouldn’t be able to stay in the house.

However, I had an inheritance from a distant relative, and I also had earned a chunk of dough by writing Math Magic for Scott Flansburg. With those amounts in hand, I could scrounge up the rest to pay off the mortgage from a couple of small investment accounts.

Over my investment adviser’s strenuous protests, I did it: Paid off the mortgage!

On several occasions, I’ve been glad I did it:

• It allowed me to show SDXB the door.
• After I was promoted to head up the university’s scholarly editing project, the increase in salary allowed me to stash a lot of money back into savings, thanks to the absence of an onerous mortgage payment.
• When I was laid off the job, I was able to hang onto the house, which would not have happened if I’d had to make mortgage payments.

Because the value of the house was pretty small, in the larger scheme of things, the tax effects of getting quit of the mortgage were nil. Maybe if the house had been worth half a million bucks or so, or maybe if I were earning a living wage, it would have made a difference. But in my circumstances, it did not.

But the question keeps coming back to haunt: was it a mistake to pay off that mortgage?

So I applied a little English-Major Math to the issue. Here’s what I came up with:

Let us imagine you can buy a house for $100,000. You can finance it at 3.5% with no down payment (it’s before the Bubble, OK?). Incidentally, you happen to have $300,000 laying around in investments; of that, about $150,000 is not in tax-deferred instruments.

What would happen if you…

a) paid the $100,000 to a lender over 30 years; or
b) paid off the $100,000 in one swell foop?

In 30 years at a 5.4% appreciation rate, your $100,000 shack will be worth $436,050. Subtract the Year 1 value of $100,000, which you paid in cash, and your net value for your house will be $336,050.

If you took that $100,000 and instead invested it in an index fund returning about 5% p.a., on average, after 30 years that fund would be worth $411,613.

At a glance, it looks like you’d do better to put the 100 grand in savings than into the house.

However…that doesn’t take into consideration the real cost of a $100,000 mortgage over 30 years.

According to Bankrate, the total interest and principal you’ll pay on that 30-year mortgage at 3.5% comes to $161,657 — not including tax and insurance. Again, it looks like we’ll do better to put the cash in a nice, calm index fund.

So, let’s think about that:

At the end of 30 years, you’ve paid $161,657 to buy a house that is now worth $457,853. The net value of the house ($437,853 valuation minus $161,657 total interest and principal payments) is $296,196.

If you had not financed the house but paid for it with $100,000 out of pocket, your net value for the house after 30 years is 357,853 (i.e., $457,853 – $100,000).

Okay, keep these figures in mind:

Finance the house: net $296,196 on sale of house 30 years later
Pay off the house: net $357,853 on sale of house 30 years later

Even though paying off the house looks better, these figures still make the $411,613 that could now be sitting in your index fund look very good. Sell the house for $296,196, and you end up with an admirable enough $707,809.

HoweEVER: what if you figured that if you could afford to fork over a monthly PITI payment to a mortgage company in the amount of about $625, you could afford to stash that amount in savings — after you’ve paid off the house?

If you invested $625 a month in a low-load index fund (Vanguard has two of them), in 30 years you would have $357,853. Let’s suppose you have the foresight to do exactly that: you pay your $100,000 in cash, and you invest the equivalent of the house payments over the course of 30 years.

Now you have a total of  $769,466 ($357,853 + 411,613). That is $60,000 more than you would have had if you’d paid that $625 a month to a lender.

These prognostications depend strongly on interest rates. Mortgage rates are still very low just now — at the present 3.4%, it makes sense to buy a house with as large a home loan as you can get. But once rates rise above about 5 percent, that changes.

Over the past 30 years, the average 30-year fixed mortgage rate has been 7.19%. At times, it’s risen over an eye-popping 16%.  The present extended period of cheap money pushes that average to a deceptively low level.

At 7.19% interest, your principal and interest payments on $100,000 would add up to $244,122 over 30 years. Now the net value of the house to you is $193,731 (i.e., $437,853 – 244,122).  That doesn’t compare well at all with the $357,853 you would net on the house had you paid out that $100,000 lo these many years ago.

So, here are four strategies, in the order of effectiveness — from most profitable to least profitable.

1. Pay off the $100,000, then invest the equivalent of principal & interest payments at 5% (your net after 30 years: $594,103: value of house + value of index fund)
2. Finance the $100,000 at 3.5%; invest the amount of the monthly mortgage payments in a low-cost index fund (you end up with $532,446)
3. Pay the $100,000; spend the payment amounts to support a better lifestyle ($336,050)
4. Finance the $100,000 with a conventional 30-year fixed-rate mortgage at 3.5% and pay principal and interest until you’re ready to fall into the grave ($296,196)

Disclaimer: Don’t believe things you read on random websites! I am not a financial advisor. I am an aging English major who prefers playing with Excel to solving crossword puzzles. None of the above constitutes or is intended to constitute financial advice.

Seven Creative Ways to Get Out of Debt

By Oliver Bochsanckel

If you have found yourself in debt, whether student loan debt or credit card debt, you may be looking for some ways to get out of it. If you want to secure your future, you need to make sure that you are always making your payments on time and keeping up with your bills.

We know that it can be difficult to maintain all of your expenses at the same time, but it is vital that you do. If you want to get out of debt quickly, you are not alone. In fact, some people take extreme measures to make sure they owe nothing and start out on the right foot.

Below, we will go over some creative ways that you can help pull yourself out of debt. We know that some of these options sound a bit off the wall, but they have helped many students and graduates move away from a life filled with debt.

  1. Use Your Reward Points

If you earn rewards points for your credit cards, for performing surveys, or even through your local electric company, think about cashing out these points and using them to pay off your debt. While it may seem like it takes forever to cash out these points, every little bit helps. When considering a new credit card, you should pay specific attention to the cash back rewards rates. Luckily for college students, student credit cards typically have high cash back rates which makes it easy to capitalize on rewards.

For example, some cash rewards programs offered by banks for taking surveys will allow you to cash out when you hit 20 points. Typically, every couple of points fetches you a dollar amount that can then be claimed as a cash reward or even on a gift card.

  1. Have a Yard Sale

If you are tired of seeing a bunch of items lying around your house, consider having a yard sale. You will be able to declutter your space while making extra money too.

One of the best ways to make your yard sale a success is to get rid of duplicate items and price within reason, so that others will purchase the items. For instance, if you have a microwave you no longer use, slap a $5 or $10 sticker on it and it will fly off the table like a hot cake. Another easy way to make your sale a success is to advertise on craigslist.

Remember, when people go to yard sales, they do not expect to pay retail, so if you have an item that you think is worth more than a couple bucks, save it and sell it later on.

Any money you collect from your yard sale can be applied to your debt. Every little bit makes a difference.

  1. Enter Contests and Giveaways

While it may be a long shot, if you have the chance to enter a contest or giveaway, do it. You never know when your luck might change and you may win that local $1,000 reward offered by your local grocery store. It is worth it in the end to at least try. Imagine if you did win, you could climb a couple of rungs to help get you out of debt.

  1. Start a GoFundMe Page

You never know who may donate to help you get out of debt. Start a GoFundMe page and share it with your friends and family. Each person can make a donation to help you climb your way out of debt.

  1. Open a Small Business

While you may have never thought to open your own business, it doesn’t hurt to do it temporarily to help pay down your debt. In fact, having a small business will allow you to set your own hours and allow you to work when you want to. This also means that you can have another job on the side without the two clashing together.

When you start to think about business ideas, think service related such as pet sitting, dog walking, lawn mowing, etc.

  1. Cash in Your Change

If you have change lying around your house, it does add up. Collect all of your change from your pockets, couch, and anywhere else you may store it and head to your local bank or to a local establishment that has a Coin Star or similar. Since you were not using this extra change for anything, simply apply it toward your debt. If you do this once a month, you may be able to send in an extra $25 or $50.

  1. Coupon

Food is a necessity, but it does not have to be expensive. Spend some time couponing on the weekends and you will quickly find that you can cut your grocery bill in half. You may even receive some free items!

If you are looking for ways to get out of debt, start with these seven creative ones and soon you will find yourself much closer to a debt-free life.


Managing Your Money: Check Out This App!

Alex Moreno is a member of the Phoenix FinCon local. He’s created a cool app, called Balance My Portfolio to help keep your investment portfolio balanced in a timely and efficient way.

The idea of systematic rebalancing, he says, is “to bring your allocation back in line with your risk tolerance.” The app works toward this goal, and it also helps you to buy low and sell high. “When one asset class has gained more than another,” he explains, “this app tells you to lock in some of the gains by selling high and moving the profits into the asset class that is at a discount.

Balance My Portfolio — check it out!

ONLY in Arizona!

You’ve gotta see this one to believe it. Truly, only in Arizona could a candidate for public office bear such an apt name…and have the effrontery to run with such frank (heh) honesty about the character of our fine leadership.

At first I thought this was a joke when my friend from Massachusetts sent it over. Educated Easterners tend to think all things associated with the State of Arizona are a joke.

Googled the guy. Yep: he shows up in a New Times article. But New Times is an alternative weekly, one that’s occasionally given to sleaze and often given to irony. The article itself could be a joke. Though it wasn’t dated April 1, we still have to classify it as dubious.

An article in the East Valley Tribune suggests there really is such a person, and that in the past he has, shall we say, exaggerated his role in the installation of rubberized asphalt on the Valley’s fine freeways. On the other hand, no daily papers in the state are great, and the Trib is one of the lesser stars in a dim constellation. Still dubious.

But then we have this. Holy sh!t.

There IS a Frank Schmuck, and he has run for public office before. The Tucson Citizen, which in 2008 was a halfway decent newspaper, reports that the Citizens Clean Elections Commission was investigating the guy for complaints that he violated the Clean Elections Law, failed to report expenses for a fundraiser, failed to report vendors providing services, and exceeded the maximum amount for early contributions from supporters.

Yup.  The man is ideal for the Arizona State Legislature. Li’l Abner’s ideel representative.

Check out the disclaimer at the bottom of the guy’s page:

Paid for by Team Schmuck. Use of Military Rank, Job Titles, or Photographs in Uniform Does Not Imply The Endorsement of The Department of Defense.

Probably the Fourth of July is not the best time for a candidate to assure us that he doesn’t endorse the Department of Defense.

On the other hand, it does brand him as a member of Arizona’s ill-educated Good Ole Boys Club, whose members are graduates of a public school system that consistently ranks among the nation’s bottommost three. In this state, not understanding the difference between “of the Department of Defense” and “by the Department of Defense” — or how to use capitalization in title case — is actually a qualification for public office.

😀

Happy Fourth of July!

  Happy Independence Day to one and all!

So what are you doing to celebrate, if anything?

Here in the ’hood, the neighborhood association throws a big shindig in the park. When the dogs and I circumnavigated the park at 5 this morning, folks were out there setting up booths and bringing in the beloved fire truck and generally carrying on. It’s a great tradition, especially for those who have the stamina to tolerate the heat…it’s supposed to hit 109 today.

Not for me, thanks. The dogs and I trotted through our favorite part of the ’hood before the Old Guy who likes to feed other people’s critters. The shade-tree mechanic’s old yaller cat was sitting on the sidewalk  awaiting the arrival of the food hand-out. Cassie, who adores cats, and Ruby, who thinks a cat might be good to eat, admired the cat quietly, sat around and gazed at the cat, did not try to grab the cat while it sat there gazing at them. LOL!

Dropped the dogs off back at the house and then raced back out to get a real walk & jog, not possible when you have one dog trying to charge forward and one dog lagging behind, pleading old age as an excuse to sniff every blade of grass. Hence the view of the shindig preparations.

This evening I’ll be joining friends at the home of a couple who host dinner at their 12th-floor apartment, which overlooks the Phoenix Country Club and the Steele Indian School Park, both of which have spectacular fireworks displays. It’s a wonderful party and experience — a great opportunity to get together with people who scatter during the summer and a fantastic view of the nearby displays and more distant fireworks all over the Valley.

So that will be fun.

People started blasting away with amateur fireworks last night. For years, selling fireworks to the general public was illegal in Arizona.

But of course, our moronic legislators decided that this outrage abridged good old American Liberty and so passed a law legalizing sale of fireworks to one and all. In Arizona, it’s perfectly legal to blow your hands off — we have affirmed that it’s your God-given American right to do so.

Cities, whose emergency responders were already maxed around the Fourth, subsequently passed local bans within city limits. The legislature, incensed, responded to this rebellion by decreeing that all retailers would be free to sell fireworks, even in cities that ban the use of fireworks. This means you can buy whatever your little heart craves at the corner Albertson’s or Safeway.

Isn’t that cute? No more stealth trips to Nogales! 🙄

So of course, at this time of year every nitwit in the city is out throwing fireworks around.

Last night a couple of bird-brains who live nearby were setting off cherry bombs. You could tell by the sound when they’d put one under a can or a pail. They were in the alley and the street outside my east wall.

Corgis being fairly calm dogs, the hounds weren’t unduly alarmed, though they didn’t like the noise. I was annoyed, in the way stupidity has always annoyed me.

In junior high school, a kid I knew was blinded when a cherry bomb he set off  under a can blew up in his face. So my patience level with this kind of “fun” is low.

vinesaroundpoolIt’s SO hot and SO dry this summer, I’m concerned about the flammability of those massive hanging gardens of cat’s-claw vines that ensure my privacy in the backyard.

Even though Gerardo has them trimmed up off they ground where they lop over the wall into the alley, there’s still masses of plant material along the way out there. All it would take is some Roman candle to go astray and land in that stuff to set fire to it. If such a fire isn’t put out quickly, it will easily jump to the house. Those vines come all the way up to the back of the house along that far wall, and they join up with hop bushes and a tree that would carry flames to the roof and attic.

So I’m not real happy about having to go off and leave the dogs here unattended. Cassie has never figured out how to use the dog door, and I doubt if Ruby would have enough sense to get out if the house started to burn. What they’d do is try to shelter in their den in the back bathroom. Where, you may be sure, they wouldn’t last long.

How can a species that so prides itself on its allegedly superior brain be, collectively and individually, so fuckin’ stupid?

I’m thinking about taking the dogs down to M’hijito’s house on the way to my friends’ place. But a) that will require me to leave very early and b) I suspect he won’t appreciate it. He’s probably entertaining his own friends.

So this morning I asked the neighbor across the street, who was celebrating the start of Independence Day by working on his wife’s car’s brakes, if he’d kinda keep an eye out. He no doubt thinks I’m a crazy old lady. But that’s OK, if he’ll take a glance over at the shack after the racket settles down.

Meanwhile, I’m pouring the water to those vines, in hopes that they’ll soak up enough moisture to protect them some from incidental sparks. Don’t even know if that’s possible. But they need to be watered, anyway.

DuckDuck is in the pool as we scribble. Every time Ruby realizes the duck is paddling around, she trots out the dog door, parks herself by the fence, and sits there as rapt as a little kid at the zoo. It’s really very adorable!

Better get up and fix some lunch and make up the rest of those tomatoes into gazpacho. And so, away! Have a happy Fourth of July!

The Food Blast: What to Do with It

So the kitchen still overflows with produce after yesterday’s serendipitous visit from the food rescue charity. OMG, you never saw so much food in this kitchen!

Yesterday evening M’hijito came over for dinner: a kind of “hot dish” lasagne that was not lasagne; sliced eggplant layer + cheese layer + sauce layer + different cheese layer + Costco pasta layer + cheese layer + different cheese layer + sauce layer + grated Parmesan layer. Made the sauce from some of the tomatoes.

Pretty good.

So far today I’ve made a tomato soup, using six more of the gigantic cardboard-flavored beefsteak tomatoes and a couple of summer squash. It’s pretty good, having been saved by some pork broth that I stuck in the fridge after cooking up a bunch of muy cheapo Costco pork for the dogs. And by the dregs of a bottle of wine M’hijito brought over last night.

TomatoSoup

Mostly it tastes of onion, celery, carrot, garlic, pork broth, and red wine. But it looks pretty, eh? I also added a little Pomì brand packaged tomatoes — Italian tomatoes that really are very tasty, indeed. But it wasn’t enough to goose the essence de tomate much.

The result has a nice enough flavor now, even if it doesn’t taste much like tomato. 🙄 I figure it’ll be good to add things TO: heat a handful of shrimp in a pan of it, for example. Once it’s packed away, it should also provide the basis of many light meals.

LOL! I won’t have to buy groceries until that outfit comes back around next month!

A half-dozen giant flavor-free tomatoes are still sitting on the counter. Those need to be converted into gazpacho, but to do that I’ll need to pick up a bell pepper, a bottle of tomato juice, and maybe some more cheap red wine.

As soon as I backwash the pool again (! …we’re having a little maintenance issue today…), I’ll go out, get those things, come back into the sauna that is my house, and build several quarts of gazpacho.

Then put a couple of the summer squash to marinate so as to grill them for dinner tonight, and then refrigerate the rest and the two pretty eggplants to be made into ratatouille tomorrow.

It is just. too. bloody. HOT in here to spend any length of time running the stove or the oven.